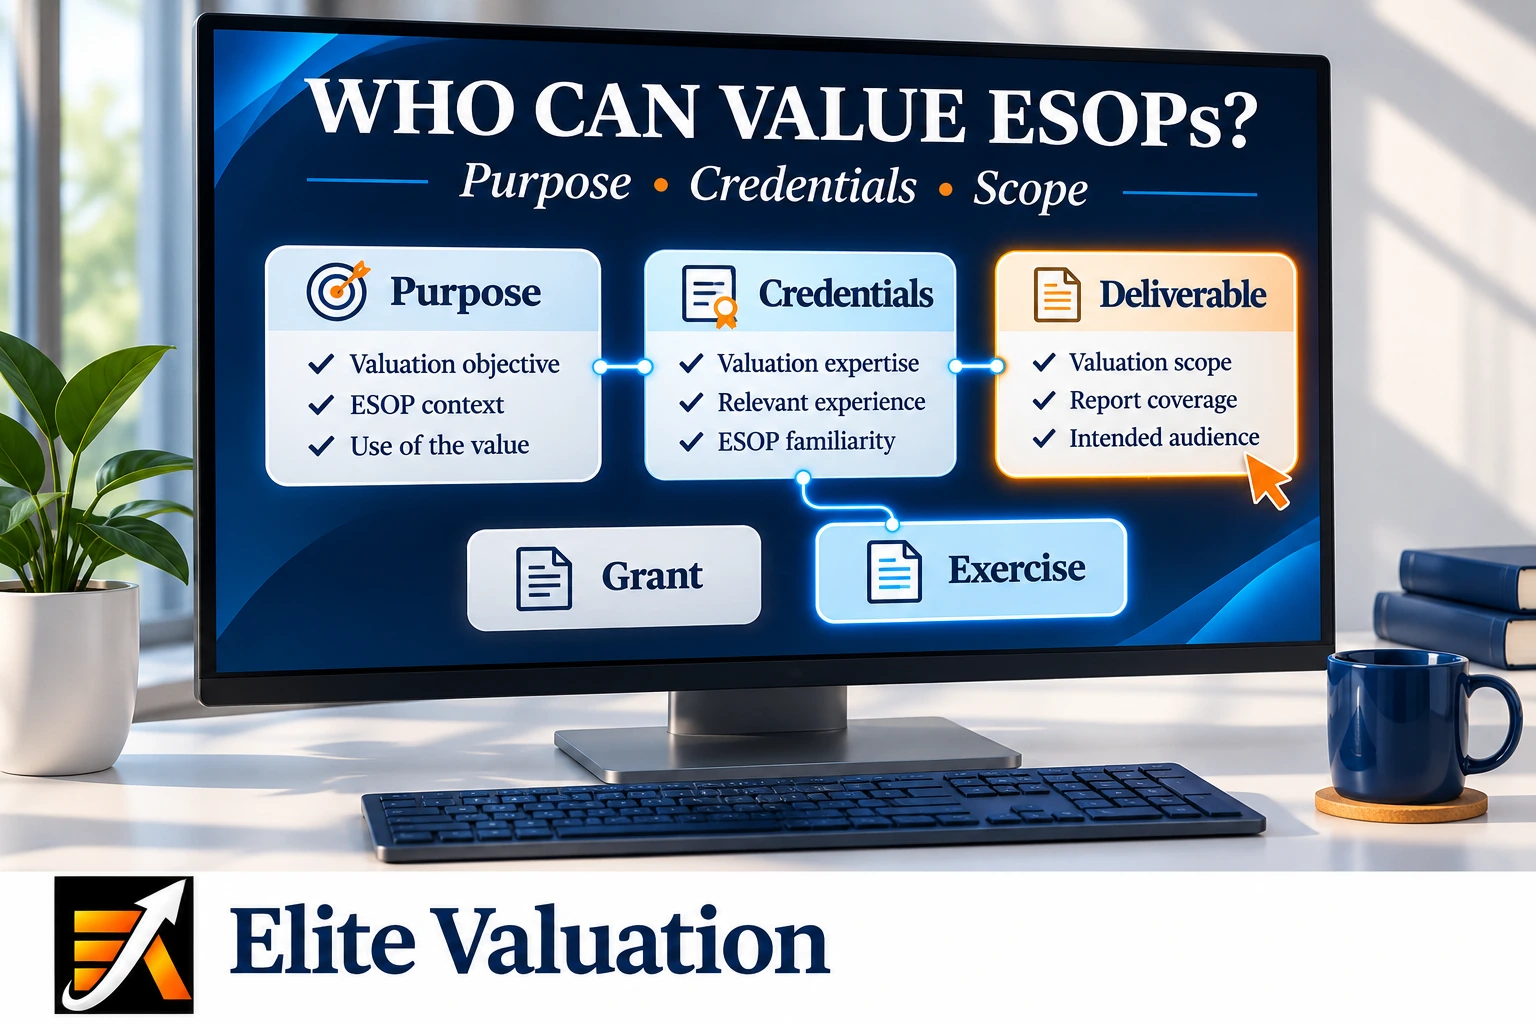
Founders and CFOs often ask one question and get two answers. The professional who values an ESOP at grant is not always the one who certifies the value on exercise. This guide separates the two and explains the credentials and scope to check before appointing either professional.
It depends on the purpose and date. An IBBI Registered Valuer is commonly engaged for grant-date option fair value. For the exercise-related fair market value of unlisted equity shares, Rule 15(6)(d) of the Income-tax Rules, 2026 names a Category I merchant banker. SEBI’s November 2026 informal guidance also addresses the merchant banker’s valuer registration under Section 247. Check both the tax requirement and the provider’s regulatory eligibility before appointing the certifier.
Key takeaways
- Grant-date and exercise-related Valuations answer different questions and have distinct professional requirements.
- The Companies Act does not expressly require a registered valuer for unlisted ESOP grants, though most companies engage one.
- For listed-company sweat equity, Regulation 34(1) requires an independent registered valuer for the know-how, intellectual property rights or value addition being contributed.
- For unlisted exercise-date values, the Income-tax Rules name a merchant banker. Confirm the certifier in writing.
Who Can Value ESOPs? The Short Answer
The answer changes with the date. The table maps each Valuation to its usual professional and the rule that drives the choice.
| Purpose | Usual professional | Basis and status |
|---|---|---|
| Grant-date fair value for the Ind AS 102 expense (unlisted) | IBBI Registered Valuer, Securities or Financial Assets | Ind AS 102. The Companies Act rules reviewed do not expressly require a registered valuer. |
| Exercise-date fair market value for perquisite tax (unlisted shares) | Category I merchant banker | Rule 15(6)(d), Income-tax Rules, 2026. Check the merchant banker’s eligibility and Section 247 valuer registration in light of SEBI’s November 2026 informal guidance. |
| Know-how, intellectual property rights or value addition contributed for listed-company sweat equity | Independent registered valuer under Section 247 | Regulation 34(1), SEBI Share Based Employee Benefits and Sweat Equity Regulations, as amended in December 2025. This is not a blanket rule for every ESOP grant valuation. |
| Pricing of shares issued to non-resident employees or investors | Chartered accountant, SEBI-registered merchant banker or practising cost accountant | FEMA (Non-Debt Instruments) Rules, 2019, Rule 21. Confirm the pricing rule applies. |
Whether the company is in Ahmedabad, Noida, Gurugram, Delhi or Pune, the certifier must match the rule for the date. Many guides treat the registered valuer as a legal requirement for grant pricing. The text reviewed does not show that for unlisted companies, so this guide presents the registered valuer as the recognised route, not a statutory mandate.
Grant-Date ESOP Valuation: The IBBI Registered Valuer’s Role
The grant-date Valuation sets the fair value of each option on the grant date. Ind AS 102 uses that figure to measure the expense over the vesting period, adjusted for awards expected to vest.
An IBBI Registered Valuer registered for Securities or Financial Assets under Section 247 is the usual professional for this report. It should state the Valuation date, the equity value of the ordinary shares, the option-pricing method and each input with its source. Companies in Pune and Gurugram with several share classes should say which class each grant relates to.
Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014 leaves the exercise price to the company, in conformity with applicable accounting policies. A chartered accountant’s certificate can support the workings, but investors and auditors usually expect a registered valuer’s report with a method note and an assumptions table.
Exercise-Date ESOP Valuation: The Merchant Banker Question
On exercise, the difference between the applicable fair market value and the exercise price is a salary perquisite. For tax years governed by the Income-tax Act, 2025, the relevant provisions are Section 17(1)(d) and Section 17(4)(h). The earlier reference was Section 17(2)(vi) of the Income-tax Act, 1961. Apply the legislation governing the relevant tax year.
For unlisted equity shares, Rule 15(6)(d) of the Income-tax Rules, 2026 requires a merchant banker’s determination; Rule 15(8)(g) defines that professional as a Category I merchant banker registered with SEBI. Rule 15(8)(l) permits the exercise date or a specified date no more than 180 days earlier. A fresh certificate is therefore not automatically required for every exercise window: confirm that the determination covers the relevant exercise.
How SEBI’s Merchant Banker Rules Fit With the Tax Requirement
The SEBI Merchant Bankers Amendment Regulations, 2025 took effect on 3 January 2026. In its informal guidance of 16 November 2026 to Navigant Corporate Advisors Limited, SEBI states that a merchant banker undertaking valuation activity must obtain registration from the relevant regulatory authority, including valuer registration under Section 247. The letter is fact-specific departmental guidance, not a Board decision, and does not amend the separate income-tax valuation rule.
A registered valuer’s report alone does not replace the Category I merchant banker determination required by Rule 15 for unlisted equity shares. Check the merchant banker’s registration, valuer registration and permitted activity structure with your advisers before the exercise window opens. Companies in Delhi and Noida should appoint the certifier before the first exercise.
Not Sure Who Certifies Your Next Exercise?
Send us the exercise windows and cap table. We will confirm the professional for each date, in writing.
Discuss your exercise windowIBBI Registered Valuer vs Category I Merchant Banker: Side-by-Side Comparison
Fee bands depend on scope, so the table names the cost drivers rather than publishing a range.
| Feature | IBBI Registered Valuer | Category I Merchant Banker |
|---|---|---|
| Registered with | IBBI, under Section 247 of the Companies Act, 2013 | SEBI, under the SEBI (Merchant Bankers) Regulations, 1992 |
| Asset class or scope | Securities or Financial Assets for shares | Permitted activities under Regulation 13A |
| Typical use | Grant-date Valuation and Ind AS 102 support | Exercise-related fair market value for unlisted equity shares under Rule 15(6)(d) |
| Current position | Independent registered valuer for the contribution valuation covered by listed-company sweat-equity Regulation 34(1) | Valuation work subject to Regulation 13A and SEBI’s November 2026 guidance |
| Validity | Tied to the grant date; refresh on any material change | Must cover the exercise, applying Rule 15’s permitted specified-date window |
| Cost drivers | Cap table complexity, number of grants and share classes | Number of exercise windows, exercises and certificate scope |
Companies in Ahmedabad, Noida and Gurugram often ask which professional is cheaper. Engage the professional the rule names for each date, then compare fees for the same scope.
Compare Fees for the Same Scope
Share your grant dates and share classes. We will quote both deliverables on one basis.
Request a scoped quoteSpecial Cases: Listed, Pre-IPO, FEMA and Both Professionals in One Year
Listed companies under SEBI’s employee scheme rules
For listed-company sweat equity, the December 2025 SEBI amendment replaces the merchant banker with an independent registered valuer under Regulation 34(1), which concerns know-how, intellectual property rights or value addition. It does not impose that requirement on every ESOP accounting valuation. The amendment commences on the thirtieth day from Gazette publication and contains an ongoing-assignment transition provision. Apply its precise scope to the work being commissioned, rather than using one transition deadline for every employee scheme.
Companies preparing to list
A company that grants options before listing values them on the unlisted basis at each grant date. Once listed, SEBI’s rules govern later grants. Companies in Delhi and Ahmedabad preparing for an IPO should map, with counsel, which grants fall either side of listing.
Cross-border employees and FEMA
For options issued to eligible persons resident outside India, Form ESOP is due within 30 days of issue of the options. If equity instruments are subsequently issued on exercise and the issue is reckoned as FDI, Form FC-GPR is due within 30 days of that issue. These reporting duties arise under the FEMA Mode of Payment and Reporting of Non-Debt Instruments Regulations, 2019. Where Rule 21 pricing applies to an unlisted-company share issue, the named certifiers are a chartered accountant, SEBI-registered merchant banker or practising cost accountant. Registered-valuer status alone is not the listed qualification; confirm applicability with your FEMA adviser.
When both professionals are needed in the same year
A company that grants options in one year and sees exercises later needs both professionals. Use one set of inputs for both so the figures reconcile, and record the reason where the share value moves between the two dates.
Which Case Applies to Your Company?
Tell us, and we will map the certifier and deliverable for each date.
Talk to Elite ValuationWhere Companies Go Wrong When Choosing Who Can Value ESOPs: Common Mistakes
Most valuer-selection errors come from trusting a label, reusing a document, or copying a rule without checking its scope. The six cards run from most to least damaging, and the same errors arise in Ahmedabad, Noida, Gurugram, Delhi and Pune alike.
Using only an IBBI Registered Valuer for exercise-date tax
Rule 15(6) names a merchant banker for unlisted shares, so the perquisite can be reopened at assessment.
Confirm the exercise-date certifier and its Regulation 13A status with your tax adviser before each exercise window opens.
Using a merchant banker’s certificate for grant-date accounting
The grant-date value rests on a certifier whose registration may not cover Valuation work, and the auditor can challenge the expense.
Engage an IBBI Registered Valuer for the grant-date report and keep the merchant banker for exercise dates.
Relying on a CA certificate or the audit team’s own figures
The certificate may not meet the rule the perquisite depends on, and the auditor may question figures from its own network.
Ask the statutory auditor to confirm in writing its position under Section 144 of the Companies Act, 2013 before accepting internal figures.
Assuming a SEBI rule covers an unlisted company’s grant
A listed-company rule is applied to a company it does not cover, and the Companies Act conditions go unchecked.
Map the scheme to the Companies Act, 2013 and the Share Capital and Debentures Rules, 2014 first, then add SEBI rules only if the company is listed.
Ignoring the asset class on the valuer’s registration
A report signed outside the registered asset class can be rejected in audit or investor due diligence.
Check on the IBBI register that the valuer is registered under Securities or Financial Assets before signing.
Reusing an exercise-date certificate without checking its coverage
A certificate used outside the permitted specified-date window or its documented scope may not support the later exercise-related perquisite value.
Check whether the merchant banker’s determination covers the relevant exercise under Rule 15, including the permitted 180-day window. Obtain a fresh determination when needed and record the provider’s registrations.
For the wider list of errors, read our guide to common ESOP Valuation mistakes in India.
What to Check Before Appointing an ESOP Valuer
- Registration: IBBI registration with the asset class stated; SEBI registration and Regulation 13A status for any merchant banker.
- Experience: a named record of unlisted ESOP schemes and option-pricing work, with the source of peer volatility data.
- Sample report: a redacted report showing the method note, assumptions table and sign-off.
- Coordination: one named lead who ties the grant report and each exercise certificate to the same inputs.
Registration is national, so a valuer in Pune can serve Delhi or Ahmedabad. Test competence and documentation, and verify each registration on the public registers before signing.
Frequently Asked Questions About Who Can Value ESOPs in India
Can an IBBI Registered Valuer do exercise-date Valuation for ESOPs?
For unlisted equity shares, Rule 15(6)(d) requires a Category I merchant banker’s determination; IBBI registration alone does not replace it. SEBI’s 16 November 2026 informal guidance separately addresses the merchant banker’s registration as a valuer under Section 247. Check the provider’s eligibility under both regimes and the scope of the certificate before the exercise.
Is a Merchant Banker certificate mandatory for unlisted companies?
For an unlisted-equity employee perquisite, Rule 15 requires a Category I merchant banker’s determination. That is separate from grant-date accounting work. Check the provider’s SEBI registration, permitted activity structure and Section 247 valuer registration in light of SEBI’s November 2026 informal guidance. The listed-company sweat-equity rule has its own distinct scope.
Can the same firm do both grant-date and exercise-date Valuations?
Yes, if the firm holds the registration each assignment needs: IBBI registration for the grant-date report, and SEBI registration for merchant banker work. Use one set of inputs for both, so the figures reconcile, and name the professional on each report. A single engagement letter can cover both deliverables, provided each is signed by the professional the rule names.
What happens if the wrong professional issues the report?
The report may not satisfy the rule it was issued under. The perquisite value can be reopened at assessment and TDS may need correcting, and the auditor may ask for a fresh grant-date Valuation. Confirm the exposure with your tax adviser and auditor before the next grant or exercise. Ask for each professional’s registration number before the report is issued, so an error is caught early.
Does the Companies Act require a registered valuer for ESOP grant pricing?
Not expressly, on the text reviewed. Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014 lets the company set the exercise price in conformity with applicable accounting policies. Rule 8(6) does require a registered valuer for sweat equity. Most unlisted companies still engage an IBBI Registered Valuer, because investors and auditors expect one.
Do listed companies need an independent registered valuer for ESOP Valuation?
The December 2025 amendment changes the certifier to an independent registered valuer for Regulation 34(1): valuation of know-how, intellectual property rights or value addition for listed-company sweat equity. It is not a blanket requirement for every listed-company ESOP accounting valuation. Apply the relevant scheme provisions and the amendment’s commencement and transition clauses to the particular assignment.
Can a startup use an IBBI Registered Valuer for its first ESOP grant?
Yes. An IBBI Registered Valuer can prepare the grant-date report for an unlisted company, ideally before the first offer letter. Each funding round can change the share value, so refresh the report with each round. Elite Valuation’s focus is growth-stage companies preparing for a Series A, B or C round, an IPO or an exit.
Can an IBBI Registered Valuer sign a FEMA pricing certificate?
Not on the wording reviewed. Rule 21 of the FEMA (Non-Debt Instruments) Rules, 2019 names a chartered accountant, a SEBI-registered merchant banker or a practising cost accountant as certifier for unlisted Indian companies. Confirm the certifier with your FEMA adviser when non-resident employees or investors are involved. A registered valuer may still be engaged for the Ind AS 102 report, which is a separate question.
Why choose a specialist ESOP Valuation firm over a Big-4 firm?
A specialist puts its team on Valuation, ESOP and related regulatory work, so the scope, method note and workings come from the same people. Elite Valuation is led by a Chartered Accountant, Company Secretary and IBBI Registered Valuer, and works to Big-4 levels of rigour. A Big-4 firm may still suit ESOP work inside a transaction or audit it already leads.
What credentials should an ESOP valuer hold in India?
Look for IBBI registration under Section 247 with the asset class stated, and SEBI registration for any merchant banker work. A chartered accountant or company secretary adds accounting and company law depth. Sagar Shah, founder of Elite Valuation, is a Chartered Accountant, Company Secretary and IBBI Registered Valuer. Check each registration on the public registers before signing.
Summary: who to appoint for each date
Appoint an IBBI Registered Valuer for the grant-date Valuation, and confirm the exercise-date certifier against Rule 15(6) and SEBI’s November 2026 guidance for each window. Whether the company is in Ahmedabad, Noida, Gurugram, Delhi or Pune, put both in writing before any engagement starts.
Get the Right Professional for Each Date
Send your cap table, grant dates and exercise windows. Elite Valuation will confirm the certifier for each figure, and the fee, in writing.
Speak to an IBBI Registered ValuerGrant-Date Valuation | Exercise-Date Support | Ind AS 102 Workings | Scheme Design
Related guides
Sources
- Income-tax Rules, 2026: Rule 15 on employee perquisites and the specified-date window.
- SEBI informal guidance to Navigant Corporate Advisors, 16 November 2026: Regulation 13A and valuer registration.
- SEBI Share Based Employee Benefits and Sweat Equity (Second Amendment) Regulations, 2025: Regulation 34(1).
- Ministry of Corporate Affairs: Companies Act, registered-valuer rules, Share Capital and Debentures Rules, and Ind AS 102.
- Reserve Bank of India: Master Direction on Foreign Investment in India, including pricing guidelines and links to the FEMA reporting regulations.
Disclaimer. This article provides general information, not legal, tax, accounting or investment advice, and is not a Valuation of a company, option or share. Requirements depend on the company, scheme, relevant date and applicable framework. Obtain advice appropriate to your circumstances.