📌 For AIF Managers, Merchant Bankers & Fund Sponsors — What You Must Know
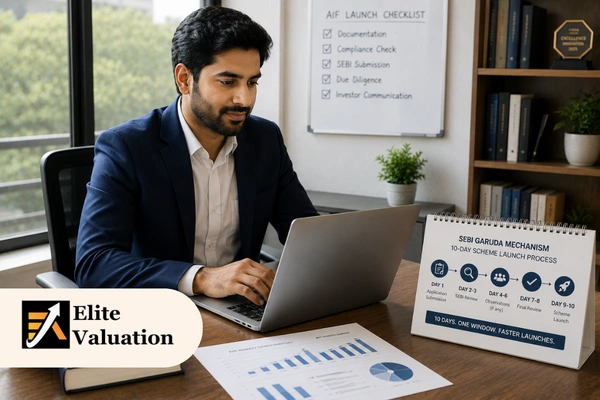
SEBI's GARUDA (Green-Channel: AIF Rollout Upon Document Acknowledgement) mechanism replaces the old wait-for-SEBI's-comments process with a fixed clock: regular AIF schemes can launch 10 working days after filing the Placement Memorandum (PPM), unless SEBI specifically advises otherwise.
- Effective from the SEBI circular dated July 30, 2026, following the AIF (Second Amendment) Regulations, 2026 gazetted on July 14, 2026
- Regular schemes need an independent Merchant Banker's Due Diligence Certificate; AI-only Funds, LVFs and Angel Funds can launch immediately on filing, without one
- Filing a PPM under GARUDA does not mean SEBI has approved it — the manager and merchant banker carry full responsibility for disclosure accuracy
For years, the single biggest source of fundraising uncertainty for an Indian AIF manager was not the fundraising itself — it was the calendar. A Placement Memorandum could sit with SEBI for weeks or months awaiting comments, with no fixed date a manager could commit to an anchor investor or an internal launch event. That uncertainty has now been substantially removed. With the GARUDA mechanism, SEBI has moved to a model where eligible schemes can proceed to launch on a defined clock, while placing considerably more responsibility on the merchant banker and the AIF manager for the quality of what is actually filed.
This shift matters commercially and operationally. A manager who has spent months building an anchor pipeline can now give investors a credible launch date the day the PPM is filed. But it also means the safety net of SEBI pre-vetting every disclosure is gone for regular schemes — the burden of getting the PPM right the first time has moved decisively onto the manager and the merchant banker who certifies it. At Elite Valuation, we support fund sponsors and managers through the entire AIF registration and scheme filing process, and this guide lays out exactly how the GARUDA framework works, who it applies to, and what a compliant GARUDA filing actually requires.
GARUDA sits within SEBI's broader push to streamline intermediary and fund regulation — the same disclosure-first, accountability-based philosophy that runs through recent SEBI valuation and preferential allotment norms for listed companies. Details of the operative circular are available directly from the regulator at the SEBI circular of July 30, 2026.
Key Takeaways:
- GARUDA stands for Green-Channel: AIF Rollout Upon Document Acknowledgement — a SEBI framework to speed up AIF scheme launches
- Regular AIF schemes can launch 10 working days after PPM filing, unless SEBI specifically advises otherwise
- An AIF's first scheme can launch from the date of SEBI registration or 10 working days after filing — whichever is later
- Regular schemes require an independent Merchant Banker's Due Diligence Certificate (Annexure 6) filed with the PPM
- AI-only Funds, LVFs and Angel Funds are exempt from the merchant banker route and can launch immediately upon filing
- AIOF/LVF/Angel Fund filings instead need a signed CEO and Compliance Officer undertaking (Annexure 7)
- New AIOF schemes must carry the suffix "AI only Fund" or "AIOF"; new LVF schemes must carry the suffix "LVF"
- Filing a PPM under GARUDA is not SEBI approval — the manager and merchant banker remain fully liable for disclosure accuracy
What Is the SEBI GARUDA Mechanism for AIFs?
GARUDA — Green-Channel: AIF Rollout Upon Document Acknowledgement — is the operating name SEBI has given to a revised process for filing and processing the Placement Memorandum (PPM) that every Alternative Investment Fund must file before launching a scheme. Under Regulation 12 of the SEBI (Alternative Investment Funds) Regulations, 2012, an AIF may launch a scheme subject to filing its PPM with SEBI through a SEBI-registered Merchant Banker. What GARUDA changes is not that requirement itself, but the timeline and the gatekeeping model sitting behind it — moving from an indefinite, comment-driven review to a fixed, acknowledgement-driven clock.
SEBI's board approved the GARUDA framework at its meeting on June 19, 2026. It was given statutory force through the SEBI (Alternative Investment Funds) (Second Amendment) Regulations, 2026, notified in the Gazette on July 14, 2026 (Gazette Notification No. CG-MH-E-14072026-274483). The operational mechanics were then laid out in a SEBI circular dated July 30, 2026 (Notification No. HO/19/19/11(2)2026-AFD-RAC2/I/17617/2026), which substituted paragraph 2.4 of the SEBI Master Circular for AIFs dated June 3, 2026 with a new paragraph titled "Modalities for filing of PPM and launch of Regular schemes."
📌 GARUDA at a Glance
- Full form: Green-Channel: AIF Rollout Upon Document Acknowledgement
- Board approval: SEBI board meeting, June 19, 2026
- Legal basis: SEBI (AIF) (Second Amendment) Regulations, 2026 — gazetted July 14, 2026
- Operational circular: July 30, 2026, substituting Para 2.4 of the Master Circular for AIFs (June 3, 2026)
- Underlying provision: Regulation 12, SEBI (AIF) Regulations, 2012
- Core change: Fixed post-filing launch clock replaces open-ended SEBI review for eligible schemes
The circular also formally defines three terms that anchor the entire mechanism. A "Regular scheme" is any AIF scheme other than a Large Value Fund (LVF), an Accredited Investor only Fund (AIOF), or an Angel Fund scheme. "Launch" is defined specifically as the circulation of the Placement Memorandum to investors for the purpose of soliciting commitments — not the date of SEBI filing itself. And "Working days" excludes weekends and any day on which the relevant SEBI office is closed, which matters when a manager is counting down to a launch date.
Why Did SEBI Introduce GARUDA? The Problem It Solves
Reform Rationale Phase
India's AIF industry has grown to more than 1,700 registered funds, with cumulative commitments of roughly ₹15.74 lakh crore and investments of around ₹6.45 lakh crore as of December 2025. At that scale, an open-ended, comment-driven PPM review process creates a real drag on capital formation — a manager cannot commit an anchor investor to a hard closing date, cannot plan a launch event, and cannot give a placement agent a firm timeline, because the review clock has no defined end point. GARUDA is SEBI's response to that specific friction: a consultation process was initiated in May 2026, the board cleared the framework in June, and the detailed operational circular followed in July — a compressed timeline that reflects how high a priority faster capital deployment has become for the regulator.
The trade-off is deliberate and openly stated in the circular: SEBI is shifting from an ex-ante gatekeeping model, where the regulator reviews disclosures before a scheme reaches investors, to an ex-post accountability model, where the scheme can reach the market faster but the manager and merchant banker are held to a much higher standard of proven diligence if something in the PPM turns out to be wrong. This is consistent with the direction SEBI has taken across several recent AIF reforms — including the introduction of the Accredited Investor only Fund category and the lowering of the Large Value Fund threshold — all aimed at giving sophisticated, well-capitalised investors faster access to products while reserving the heavier compliance burden for retail-facing structures.
How Does the 10-Working-Day Launch Window Work for Regular AIF Schemes?
For a Regular scheme — meaning any scheme other than an LVF, AIOF or Angel Fund — paragraph 2.4.1.1 of the revised Master Circular sets out two distinct clocks depending on whether the scheme is the AIF's first or a subsequent one.
| Scenario | Earliest Permitted Launch Date | Governing Clock |
|---|---|---|
| New scheme of an already-registered AIF | 10 working days after PPM filing with SEBI | Filing-acknowledgement clock, unless SEBI advises otherwise |
| First (maiden) scheme of a newly registered AIF | Date of SEBI registration or 10 working days after filing — whichever is later | Dual clock — registration and filing, later of the two governs |
The "unless otherwise advised" clause is important and is frequently glossed over. SEBI retains the ability to flag a specific filing and delay the launch clock — GARUDA removes the default wait, but it does not remove SEBI's supervisory power over an individual filing that raises concerns during the 10-working-day window. A manager treating the 10-day mark as an absolute, unconditional launch date without confirming there has been no SEBI advisory is taking on avoidable risk.
Illustrative Timeline — Regular Scheme, Subsequent Launch
Category II AIF — Private Credit Scheme
Regular Scheme
An existing, SEBI-registered Category II AIF wants to launch its third scheme, a private credit fund. The merchant banker completes due diligence and the PPM, with all supporting annexures, is filed on the SEBI Intermediary Portal on a Monday. Counting only working days and assuming no SEBI advisory is issued, the scheme becomes eligible for launch — meaning the PPM can be circulated to investors to solicit commitments — after 10 working days, roughly two calendar weeks later depending on holidays.
<p⚠️ "10 Working Days" Is a Floor, Not a Guarantee. The clock only starts once the PPM filing is acknowledged and is treated as complete. An incomplete filing, a missing annexure, or a query flagged by SEBI within the window can reset or extend the effective timeline. Building the 10-working-day window into a fundraising calendar as the single point of failure, without a buffer, is one of the most common execution mistakes we see managers make in the first few months of GARUDA.
What Documents Must Be Filed With the PPM Under GARUDA?
Paragraph 2.4.1.2 of the revised Master Circular requires that, for Regular schemes, the PPM be filed — either at the time of the AIF's registration or prior to the launch of a new scheme — on the SEBI Intermediary Portal, accompanied by a specific set of supporting documents and the applicable scheme fee.
📋 Documents Required With a Regular Scheme PPM Filing
- Merchant Banker Due Diligence Certificate (Annexure 6)
- Fit and Proper declarations for the AIF, sponsor and manager
- Sponsor/manager declaration confirming the minimum continuing interest commitment
- PAN details of the AIF, the scheme (where available), the sponsor, the manager, the trustee, directors/partners, and key investment team members — compiled in a single Excel, Word or PDF file
- Payment of the applicable scheme filing fee
The requirement to consolidate PAN details for every director, partner and key investment team member into a single file is a small but deliberate design choice — it is meant to let SEBI cross-check fit-and-proper status and past regulatory history across every individual connected to the scheme quickly, without the back-and-forth that used to slow down manual review. Managers who treat this as a formality and submit an incomplete or inconsistent PAN list are the most common reason a filing gets flagged inside the 10-working-day window.
What Is the Merchant Banker's Expanded Role and Liability Under GARUDA?
Due Diligence & Accountability Phase
Due Diligence & Accountability Phase The merchant banker is the load-bearing wall of the GARUDA framework for Regular schemes. Because SEBI no longer independently reviews every disclosure before launch, the diligence that would previously have happened partly inside SEBI now has to happen entirely, and verifiably, at the merchant banker's desk before the PPM is even filed.
What GARUDA Requires of the Merchant Banker
Independence Mandatory
Due Diligence Certificate Required
- Must be independent — cannot be an associate of the AIF, its sponsor, manager or trustee
- Must independently verify the veracity and adequacy of every material disclosure in the PPM
- Must submit a Due Diligence Certificate (Annexure 6) confirming the disclosures enable investors to make an informed decision
- Must be named and disclosed within the Placement Memorandum itself
- The PPM must carry a disclaimer confirming the merchant banker has independently verified the disclosures and that the document complies with applicable regulations
The independence requirement is a meaningful change in practice. Fund managers who previously routed PPM filings through an affiliated or in-house-adjacent merchant banking arm now need to engage a genuinely unconnected SEBI-registered merchant banker — which affects both timeline planning (an external merchant banker needs lead time to complete diligence before the clock even starts) and fee budgeting for the launch.
⚠️ Diligence Quality Is Now the Primary Line of Defence. Because SEBI's own review is no longer the safety net it once was for Regular schemes, a merchant banker who signs a Due Diligence Certificate without genuinely testing the PPM's factual claims — track record figures, key-person continuity, fee disclosures, conflict-of-interest statements — is taking on direct regulatory exposure that a lighter-touch review under the old process would not have carried.
How Do AI-Only Funds, LVFs and Angel Funds Get Immediate Launch Under GARUDA?
The most consequential relief under GARUDA is reserved for schemes serving the most sophisticated investors. Accredited Investor only Funds (AIOFs) and Large Value Funds for Accredited Investors (LVFs) — where each investor is accredited and commits a minimum of ₹25 crore per the threshold reduced from the earlier ₹70 crore requirement under the SEBI (AIF) (Third Amendment) Regulations, 2025, notified November 18, 2025 — are exempt from the merchant banker filing route entirely. These schemes can launch immediately upon filing the PPM with SEBI, and a fund's first AIOF or LVF scheme can launch from the date of SEBI registration itself.
Angel Funds receive parallel treatment under the SEBI (AIF) (Second Amendment) Regulations, 2026. They are exempt from the merchant banker route and may begin circulating their Placement Memorandum to investors immediately after obtaining SEBI registration — without waiting on any filing-based clock at all.
| Scheme Category | Merchant Banker Required? | Earliest Launch | Filing Undertaking |
|---|---|---|---|
| Regular scheme | Yes — independent MB mandatory | 10 working days after PPM filing | MB Due Diligence Certificate (Annexure 6) |
| AI-only Fund (AIOF) | No | Immediately upon PPM filing | CEO + Compliance Officer undertaking (Annexure 7) |
| Large Value Fund (LVF) | No | Immediately upon PPM filing | CEO + Compliance Officer undertaking (Annexure 7) |
| Angel Fund | No | Immediately upon SEBI registration | CEO + Compliance Officer undertaking (Annexure 7) |
n place of the merchant banker's Due Diligence Certificate, AIOF, LVF and Angel Fund filings require a jointly signed and stamped undertaking from the CEO (or equivalent) and the Compliance Officer of the manager (Annexure 7), together with a corresponding disclaimer clause built into the PPM itself. Responsibility for the accuracy of the disclosures rests squarely with the manager in these cases — there is no independent third-party certifier standing between the manager's claims and the investor.
Why the Relief Is Calibrated to Investor Sophistication
₹25 Crore Minimum Per Accredited Investor
SEBI's logic here mirrors the accredited-investor framework more broadly: an accredited investor — broadly, an individual with annual income above ₹2 crore, or net worth above ₹7.5 crore of which at least ₹3.75 crore is in financial assets — is presumed capable of evaluating fund disclosures independently and negotiating protective terms directly with the manager, reducing the need for a regulator-mandated intermediary check before capital is solicited.
Not Sure Which GARUDA Category Your Scheme Falls Into?
Whether you're structuring a Regular scheme, an AI-only Fund, an LVF or an Angel Fund, the category you file under determines your entire launch timeline. We help managers map the right structure before a single document goes to SEBI.
GARUDA Naming Conventions — AIOF and LVF Suffix Rules
Alongside the procedural changes, SEBI has introduced a naming requirement designed to make a scheme's regulatory category identifiable from its name alone — useful for investors, distributors, custodians and auditors who need to quickly recognise which compliance track a scheme sits on
✔ New Naming Requirements Under GARUDA
- New Accredited Investor only Fund schemes must carry the suffix "AI only Fund" or "AIOF" at the end of the scheme name
- New Large Value Fund schemes must carry the suffix "LVF" at the end of the scheme name
- Regular schemes and Angel Fund schemes carry no mandated suffix under this specific requirement
This is a straightforward compliance point but an easy one to miss during the naming and branding stage of a new scheme launch — a marketing-driven scheme name that omits the mandated suffix is a documentation defect that can delay filing acceptance, even where every substantive disclosure in the PPM is otherwise compliant.
Does Filing a PPM Under GARUDA Mean SEBI Has Approved the Scheme?
This is arguably the single most important clarification in the entire circular, and the one most likely to be misunderstood by investors and even by some managers unfamiliar with the shift. SEBI has stated explicitly that submission of the PPM under GARUDA does not amount to SEBI approval. SEBI does not certify the correctness of the disclosures contained in the PPM, and it does not guarantee the manager's capability to run the scheme. The entire burden of accurate, complete and non-misleading disclosure sits with the manager — and, for Regular schemes, with the merchant banker who signed the Due Diligence Certificate.
🚫 Consequence of Inaccurate or Misleading Disclosures. Any incorrect, misleading or incomplete disclosure identified after a scheme has launched under GARUDA's faster timeline can trigger direct regulatory action against the manager and the merchant banker — a consequence that carries more weight than it did under the old process, precisely because SEBI did not have the opportunity to catch the defect before investors were solicited. Managers should treat this as materially higher personal and institutional risk than the pre-GARUDA filing regime.
Practically, this means the PPM disclaimer language itself — confirming independent merchant banker verification, or the CEO/Compliance Officer undertaking for AIOF/LVF/Angel Fund schemes — is not boilerplate. It is the operative document SEBI will point to when assessing where responsibility sits if a dispute or enforcement action arises later.
Preparing to File Under GARUDA in the Next Fundraising Cycle?
From merchant banker coordination to the PAN, Fit & Proper and continuing-interest documentation pack, we help managers assemble a GARUDA-compliant filing that survives the 10-working-day window without a query.
GARUDA vs the Earlier AIF Scheme Launch Process — What Changed
Understanding GARUDA is easier in direct contrast to the process it replaces. The table below summarises the practical shift for a manager planning a launch.
| Aspect | Pre-GARUDA Process | GARUDA Process |
|---|---|---|
| Launch timeline | Open-ended, dependent on SEBI's review and comments | Fixed 10 working days after filing (Regular schemes), unless SEBI advises otherwise |
| Certainty of launch date | Low — managers could not commit a firm date to investors | High — a defined, calendarable date for Regular schemes |
| Merchant banker role | Assisted with filing; diligence expectations less codified | Independent due diligence and certification mandatory, with disclosed independence criteria |
| AI-only Funds & LVFs | Subject to broadly similar filing requirements as other schemes | Exempt from merchant banker route; immediate launch on filing |
| Angel Funds | Merchant banker route generally applicable | Exempt; PPM circulation permitted immediately after registration |
| Regulatory framing of a filing | Often perceived in practice as a step toward SEBI clearance | Explicitly stated not to constitute SEBI approval |
| Where accountability sits | Shared, with SEBI's review acting as a partial check | Concentrated on the manager and merchant banker |
How Should AIF Managers and Merchant Bankers Prepare for a GARUDA Filing?
Filing Readiness Phase
1.Confirm the Correct Scheme Category Before Drafting the PPM
Determine upfront whether the scheme qualifies as a Regular scheme, an AIOF, an LVF, or an Angel Fund scheme — this single decision determines whether a merchant banker is required, what annexure applies, and how fast the scheme can reach investors. Getting this wrong after drafting has begun means rebuilding the filing pack from scratch.
2. Engage an Independent Merchant Banker Early — For Regular Schemes
Because the merchant banker cannot be an associate of the AIF, sponsor, manager or trustee, and must complete genuine due diligence before certifying the PPM, this engagement needs lead time built into the fundraising calendar — the 10-working-day clock starts only after filing, not after the merchant banker is appointed.
3. Assemble the Full Annexure Pack in One Pass
Collect Fit and Proper declarations, the sponsor/manager minimum continuing interest declaration, and consolidated PAN details for every director, partner, trustee and key investment team member into a single file before filing — an incomplete pack is the most common reason a Regular scheme filing is queried inside the window.
4. Build the 10-Working-Day Window Into Investor Communications — With a Buffer
Communicate the earliest possible launch date to anchor investors as a floor, not a guarantee, and hold back a contingency buffer for a possible SEBI advisory. Treating the 10th working day as an absolute date, without confirming filing acceptance, is a common and avoidable planning error.
5. Draft the PPM Disclaimer and Scheme Name for Compliance, Not Just Marketing
Ensure the PPM carries the mandated disclaimer — merchant banker verification for Regular schemes, or the CEO/Compliance Officer undertaking language for AIOF/LVF/Angel Fund schemes — and that the scheme name carries the correct "AIOF"/"AI only Fund" or "LVF" suffix where applicable, before the name is used in any external marketing material.
6. Treat the Filing as the Operative Compliance Record, Not a Formality
Because filing does not equal SEBI approval, the manager (and merchant banker, where applicable) should internally document the diligence performed on every material PPM claim — track record, key-person continuity, fee structure, conflicts — as the evidentiary record that would be relied on if a disclosure is later challenged.
📁 Anonymised Case Study
Category II AIF — Private Credit Manager
Third Scheme Launch
First GARUDA Filing
A Category II AIF manager with two existing private credit schemes approached us to launch a third scheme immediately after the GARUDA circular took effect, targeting a hard close with a set of returning anchor investors. The manager's initial instinct was to treat the 10-working-day rule as a simple calendar entry and had already verbally committed a launch date to investors before the PPM was drafted.
Our review flagged two issues before filing: the PAN details for two recently appointed key investment team members had not been consolidated into the required single file, and the proposed merchant banker had a historical advisory relationship with the manager's sponsor entity that could compromise the independence requirement. We helped the manager re-engage a genuinely independent merchant banker, complete the diligence process in parallel with finalising the PPM, and file a complete, correctly formatted annexure pack. The scheme launched cleanly on the 10th working day with no SEBI advisory — but the manager's original verbally committed date, set before the documentation gaps were identified, would have been missed by roughly two weeks had the issues surfaced after filing instead of before it.
Launching Your Next AIF Scheme Under GARUDA?
From scheme-category mapping and merchant banker coordination to Fit & Proper documentation and PPM disclaimer drafting, we support the full GARUDA filing lifecycle for AIF managers and sponsors.
Where AIF Managers Go Wrong Under GARUDA — Common Mistakes
❌Committing a launch date to investors before the PPM is filed and acknowledged
Treating the 10-working-day rule as a promise rather than a floor leads managers to commit dates to anchor investors before filing is even complete, leaving no room for a documentation query or a SEBI advisory.
Fix: Communicate launch timelines as "no earlier than" dates, and only confirm a firm date once the filing has been acknowledged with no advisory outstanding.
❌ Engaging a merchant banker with an existing relationship to the sponsor or manager
The independence requirement is specific and strictly enforced — a merchant banker who is an associate of the AIF, sponsor, manager or trustee cannot perform the GARUDA due diligence role, regardless of how the relationship is characterised.
Fix: Screen prospective merchant bankers for any historical advisory, ownership, or personnel overlap with the sponsor or manager before engagement, not after diligence has begun.
❌ Misclassifying a scheme to access the immediate-launch route
Structuring a scheme to nominally qualify as an AI-only Fund or LVF — without every investor genuinely meeting the accreditation and ₹25 crore commitment threshold — to bypass the merchant banker requirement creates a compliance exposure that surfaces the moment SEBI or an investor questions the classification.
Fix:Model Verify and document each investor's accreditation status and commitment amount before relying on the AIOF/LVF exemption, and default to the Regular scheme route where any investor's status is uncertain.
❌Treating the PPM disclaimer and undertaking language as boilerplate
Because SEBI has clarified that filing does not equal approval, the disclaimer and the CEO/Compliance Officer undertaking are the operative documents that establish where liability sits — copying generic disclaimer language without tailoring it to the actual diligence performed weakens the manager's position if a disclosure is later disputed.
Fix: Draft disclaimer and undertaking language to accurately reflect the specific diligence steps completed, and retain the underlying working papers as evidence.
❌Omitting the mandated AIOF or LVF naming suffix
A scheme name chosen for marketing appeal that does not carry the required "AI only Fund"/"AIOF" or "LVF" suffix is a documentation defect that can delay a filing that is otherwise fully compliant on substance.
Fix: Finalise the compliant scheme name, including the mandated suffix, before it is used in any term sheet, pitch material, or investor communication.
❌ Filing an incomplete PAN and Fit & Proper pack to save time
Submitting the PPM without fully consolidated PAN details for every director, partner, trustee and key investment team member — treating this as a document to complete "after filing" — is one of the most common reasons a Regular scheme filing gets flagged inside the 10-working-day window.
Fix: Build the PAN and Fit & Proper consolidation into the pre-filing checklist as a hard gate, not a follow-up item.
Closing Summary: GARUDA Rewards Preparation, Not Just Speed
The GARUDA mechanism genuinely compresses the AIF scheme launch timeline — 10 working days for Regular schemes, and immediate launch for AI-only Funds, LVFs and Angel Funds is a material improvement over the open-ended review process it replaces. But the framework's speed is a direct function of the diligence and documentation quality a manager and merchant banker put in before the PPM is ever filed, because SEBI has been explicit that a faster filing is not a pre-cleared one. At Elite Valuation, we help AIF managers and sponsors map the correct scheme category, coordinate merchant banker diligence, assemble a complete GARUDA annexure pack, and build a launch timeline that survives the 10-working-day window on the first attempt — so that the speed GARUDA offers is realised, not lost to an avoidable query.
Get Your AIF Scheme GARUDA-Ready — From Filing Strategy to Launch
Scheme classification → Merchant banker coordination → Documentation pack → PPM disclaimer & naming compliance → Launch. One engagement, built for managers filing under the GARUDA mechanism.
Frequently Asked Questions — SEBI GARUDA Mechanism
CA Sagar Shah, Founder
Mr Sagar Shah is the Founder of Elite Valuation and leads the firm’s Valuation and Advisory practice. With over 15+ years of professional experience.