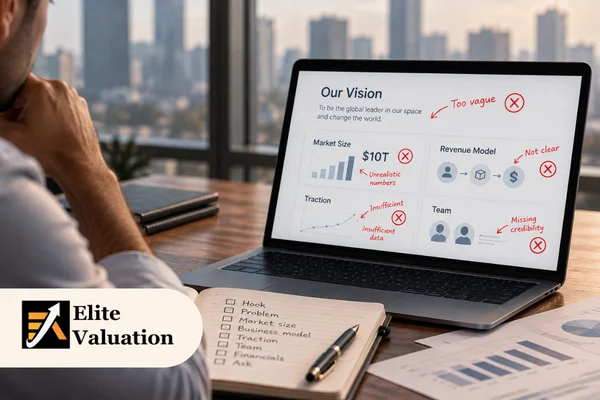
📌 For Founders: What You Must Know
- Investors read a deck to find a reason to say no. At roughly three minutes per deck, a 12-slide deck gets about 15 seconds per slide.
- A deck behaves like a series circuit. If each slide carries a 5% chance of triggering a pass, the deck survives all 12 slides only 54% of the time. At 10% per slide, survival falls to 28%.
- The five mistakes that cost the most: top-down market sizing, hidden unit economics, a missing or unsupported Valuation ask, claiming "no direct competitors", and a bloated cap table.
- Each has a price. A deck showing an LTV to CAC of 11.7x can recompute to 2.7x. An unsupported ask can cost 5.7 percentage points of ownership. A messy cap table can cost founders 5.8 points after the round.
- Every one of these mistakes can be found and fixed before the first email goes out.
Pitch deck mistakes rarely look like mistakes to the founder who makes them. A top-down market slide looks ambitious. A clean unit economics slide looks efficient. A blank Valuation line looks flexible. To the investor reading the deck, each one sends a different signal: a market that was never sized, numbers that were never recomputed, a founder who has not thought about price.
Behavioural economics explains why a single flaw can end a conversation. Kahneman and Tversky's prospect theory found that people weigh losses roughly twice as heavily as equivalent gains. An investor reading your deck is not scoring upside, because every deck shows upside. The investor is screening for the loss: the cheque that cannot be returned, the follow-on that cannot be defended, the partner meeting where a question has no answer. Each mistake below is a cheap, early signal of a large loss, and this article puts a number on each one.
At Elite Valuation, we sit on the other side of this table. As IBBI Registered Valuers and Chartered Accountants, we recompute the numbers behind decks for founders, funds and acquirers, and the same five errors repeat. For what an expert build involves, see our guide on how to hire pitch deck experts in India. For the statutory side of pricing a round, see share Valuation and Rule 57 and FEMA Valuation for foreign investment.
Key Takeaways:
- Investors skim for reasons to pass: at three minutes per deck, a 12-slide deck gets about 15 seconds per slide
- Deck survival is multiplicative: a 5% per-slide pass risk leaves a 54% chance of surviving 12 slides, and 10% leaves 28%
- 1% of a $1 trillion market is $10 billion of revenue, or 2 million customers at $5,000 each, about 783 new customers every day for seven years
- Hidden unit economics can turn an LTV to CAC of 11.7x into 2.7x and a 4.3 month payback into 12.5 months once costs are fully loaded
- A missing Valuation basis lets the investor anchor first: on an ₹8 crore round, a ₹30 crore versus ₹44 crore pre-money outcome is a 5.7 point ownership gap, worth ₹22.7 crore at a ₹400 crore exit
- "No direct competitors" cuts overall deck credibility from 59% to about 17% when five claims each fall from 90% to 70% believability
- A 10% post-money option pool turns a ₹40 crore headline into an effective pre-money of ₹37.05 crore, and a cleaner cap table is worth 5.8 points of founder ownership
- Six pre-send tests, plus reconciliation to GSTR-3B and audited accounts, catch all five mistakes before an investor does
The Psychology of VC Rejection (How Quickly They Skim)
Investor Psychology
An investor opening your deck is running a screening process, not a reading exercise. A typical venture fund sees far more decks than it can meet, so the first pass is built to eliminate. DocSend's published research has put average investor time on a deck at roughly two to four minutes, depending on the year and stage. In its 2020 data, decks that went on to raise money held attention for over four minutes, against about 1 minute 30 seconds for decks that did not. At three minutes, a 12-slide deck gets about 15 seconds per slide.
That time is not spread evenly. DocSend's early research found that investors lingered longest on the financials, team and competition slides, which is exactly where the mistakes in this article sit. A founder who spends 40 hours on design and two hours on the unit economics slide has allocated effort in the opposite proportion to the investor's attention.
Why One Flaw Outweighs Five Strengths
Loss aversion changes how a deck is read. A fund's returns are driven by a handful of outsized winners, so a partner's job is to avoid the avoidable loss while staying open to the rare upside. A flaw that signals a visible, avoidable loss is therefore weighed more heavily than a strength that signals more upside. That is why a strong growth chart does not rescue a deck whose CAC is understated.
Treat the deck as a series circuit, not a sum of strengths. If each slide carries even a small, independent chance of triggering a pass, survival compounds. The table below is an illustrative model, not a measured statistic, but the arithmetic is what matters.
| Chance Each Slide Triggers a Pass | Probability the Deck Survives All 12 Slides | Second Looks From 40 Investor Conversations |
|---|---|---|
| 2% (clean deck) | 78.5% | 31.4 |
| 5% (typical DIY deck) | 54.0% | 21.6 |
| 10% (deck with several flaws) | 28.2% | 11.3 |
Survival probability = (1 minus per-slide pass risk) raised to the power of 12. Assumes independence between slides; illustrative.
Cutting per-slide risk from 10% to 2% nearly triples the number of conversations that reach a second look (11.3 to 31.4 out of 40) without improving the underlying business at all. The business is the same. Only the deck's exposure to avoidable loss signals has changed.
📌 What a Failed Process Costs
- DocSend's 2015 research with Harvard Business School's Tom Eisenmann found founders averaged around 40 investor meetings and a little over 12 weeks to close a round
- At a monthly burn of ₹40 lakh, a three-month process consumes ₹1.2 crore of runway
- A deck that fails the first pass spends the same runway and returns nothing, so the loss is the whole process, not one meeting
What the Investor Is Silently Asking on Each Slide
| Mistake | The Investor's Silent Question | What They Do Next |
|---|---|---|
| Top-down market sizing | Can this reach venture scale, and has the founder built the market from customers? | Rebuilds the market bottom-up in minutes |
| Hidden unit economics | Do these numbers survive full costing? | Recomputes CAC, payback and LTV from the P&L |
| Missing Valuation ask | Has the founder thought about price, or will I be setting it? | Anchors the negotiation at their own number |
| "No direct competitors" | Has the founder researched the market honestly? | Finds three alternatives and discounts every other claim |
| Bloated cap table | Will this structure create friction, dead equity or weak founder incentives? | Models the post-round table and asks for clean-up |
The five sections that follow take each mistake in turn, show the bad slide, run the investor's arithmetic, and price the loss.
Mistake 1: The "Top-Down" Market Sizing Delusion (1% of a $1 Trillion Market)
Market Sizing
📌 Bad Pitch Deck Example: The Slide
"The global market for our category is $1 trillion. If we capture just 1%, that is a $10 billion business."
This is the most common of all pitch deck mistakes, and it fails because it describes a hope, not a market. The investor does not argue with the $1 trillion. The investor asks what 1% requires, and the answer is absurd within a minute.
What 1% of $1 Trillion Actually Demands
- Revenue: 1% of $1 trillion is $10 billion a year, roughly ₹90,000 crore at an illustrative ₹90 per US dollar
- Customers: at an average contract value of $5,000 a year, that is 2,000,000 paying customers
- Pace: reaching 2 million customers in seven years means signing about 285,700 a year, or roughly 783 every single day, including weekends
No founder believes the slide when it is decomposed this way, and no investor does either. Worse, the slide shows that the founder has not worked out who the first 100 customers are, what they pay, or how they are reached. Market size is not a number found in an industry report. It is a number you build.
The Bottom-Up Build Investors Expect
A defensible market slide multiplies three things you can verify: the number of target accounts, the annual contract value (ACV) you can charge, and the share you can realistically win. Take a mid-market logistics software company with an ACV of ₹6 lakh.
| Layer | Logic | Accounts | Value |
|---|---|---|---|
| TAM | All target companies in the segment × ₹6 lakh | 18,000 | ₹1,080 crore |
| SAM | 40% reachable through your channels × ₹6 lakh | 7,200 | ₹432 crore |
| SOM (year 5) | 4% of SAM accounts × ₹6 lakh | 288 | ₹17.3 crore ARR |
Account counts and shares are illustrative assumptions. Build yours from public company databases, MCA filings and your own pipeline data.
The Venture-Scale Test: Why Honest Math Can Still Fail
A bottom-up number is credible, but it must also be large enough. Investors run a return test backwards from the fund's needs. Suppose a fund invests ₹10 crore for 20% (a ₹40 crore pre-money) and wants a 10x return on that cheque.
| Step | Calculation | Result |
|---|---|---|
| Ownership at exit after two later rounds, each diluting 20% | 20% × 0.8 × 0.8 | 12.8% |
| Exit value needed for a 10x return (₹100 crore) | ₹100 crore ÷ 12.8% | ₹781 crore |
| ARR needed at a 5x revenue multiple | ₹781 crore ÷ 5 | ₹156 crore |
| Bottom-up SOM at today's ACV | 288 customers × ₹6 lakh | ₹17.3 crore (about 9x short) |
| Path with ACV expanding to ₹15 lakh through added modules | 7,200 accounts × ₹15 lakh × 15% share | ₹162 crore (clears the bar) |
The lesson is strategic, not arithmetic. The honest SOM at today's pricing is about nine times too small for a venture return. The fix is not to inflate the TAM. The fix is to show how ACV and share expand: additional modules, adjacent segments, or usage-based pricing, each with its own bottom-up logic. An investor who sees the expansion path will fund the plan. An investor who sees only a percentage of a trillion will not.
📌 What This Mistake Costs You
- The investor's venture-scale test fails silently, and you never hear why. The loss is the entire ₹10 crore cheque
- You spend another ₹1.2 crore of runway (three months at ₹40 lakh) on a process that was lost in the first minute
- A founder who cannot size a market from customers signals weak go-to-market thinking, which lowers confidence in every other slide
Mistake 2: Hiding Unrealistic Unit Economics in the Financials
Financial Credibility📌 Bad Pitch Deck Example: The Slide
"Gross margin 82%. Monthly churn 2%. CAC ₹1.4 lakh. CAC payback 4.3 months. LTV to CAC 11.7x."
These are strong numbers. They are also, in the version we see most often, wrong in three specific ways. The slide is built from the most flattering definition of each metric, and an investor's analyst rebuilds each one from the P&L within days.
The Formulas an Investor Uses
- Gross profit per customer per month = monthly revenue per account (ARPA) × gross margin
- CAC payback (months) = fully loaded CAC ÷ gross profit per customer per month
- Customer lifetime (months) = 1 ÷ monthly churn
- LTV = gross profit per customer per month × customer lifetime
- LTV to CAC = LTV ÷ fully loaded CAC
Take an ARPA of ₹40,000 a month (₹4.8 lakh a year). Here is the same business, as presented and as recomputed.
| Metric | Deck Says | Investor Recomputes | Why It Differs |
|---|---|---|---|
| Gross margin | 82% | 72% | Customer support salaries and cloud costs sit in operating expenses |
| Monthly churn | 2% | 3% | Paused and downgraded accounts are excluded from the churn count |
| CAC | ₹1.4 lakh | ₹3.6 lakh | Deck counts paid media only (₹28 lakh ÷ 20 customers); full cost adds ₹2 lakh of marketing programmes and ₹42 lakh of sales salaries (₹72 lakh ÷ 20) |
| CAC payback | 4.3 months | 12.5 months | ₹1.4 lakh ÷ ₹32,800 versus ₹3.6 lakh ÷ ₹28,800 |
| Customer lifetime | 50 months | 33.3 months | 1 ÷ 2% versus 1 ÷ 3% |
| LTV | ₹16.4 lakh | ₹9.6 lakh | ₹32,800 × 50 versus ₹28,800 × 33.3 |
| LTV to CAC | 11.7x | 2.7x | Compounded effect of all three adjustments |
The headline falls from 11.7x to 2.7x, and the payback triples. Neither founder intent nor the arithmetic was dishonest. The definitions were chosen to flatter. That distinction does not matter to the investor, who now doubts every other metric in the deck.
The Sensitivity Investors Run Next
Once the analyst has fully loaded the CAC, the next question is churn. If the customer base is small business rather than mid-market, monthly churn of 5% is realistic. Lifetime falls to 20 months, LTV falls to ₹5.76 lakh (₹28,800 × 20), and LTV to CAC falls to 1.6x. At that level the business loses money on a lifetime basis after servicing costs, and growth makes it worse.
📌 What This Mistake Costs You
- Cost of growth: adding ₹1 crore of ARR requires about 20.8 new customers (₹1 crore ÷ ₹4.8 lakh). At the true CAC of ₹3.6 lakh that costs ₹75 lakh, not the ₹29 lakh the deck implies
- Valuation: on ₹8 crore of ARR, an illustrative drop in the multiple from 7x to 4.5x moves the Valuation from ₹56 crore to ₹36 crore, a ₹20 crore gap
- Trust: the first recomputed metric makes the investor re-check every other number, and each check costs you credibility
The strategic fix is to present the investor's number first. Show fully loaded CAC with a bridge from paid media to total cost, show gross margin after support and cloud costs, and show revenue churn and logo churn separately. A founder who volunteers the harder number earns credibility that no polished chart can buy. For the metrics that drive the multiple, see our guide on SaaS Valuation, ARR, NRR and CAC efficiency.
Is Your Deck Hiding Numbers an Investor Will Recompute?
We rebuild your CAC, payback, LTV and gross margin from your books exactly as an investor's analyst will, and show you the gap before they do.
Mistake 3: The Missing or Unjustifiable Valuation Ask
Pricing Discipline
📌 Bad Pitch Deck Examples: Two Versions of the Same Mistake
Version A: "Raising ₹8 crore. Valuation: open to discussion."
Version B: "Raising ₹8 crore at a ₹90 crore pre-money, because we are building the next category leader."
Version A hands the first number to the investor. Version B offers a number with no basis. Both lose, in different ways.
Why a Blank Ask Costs Ownership: The Anchoring Effect
Tversky and Kahneman's work on anchoring showed that the first number in a negotiation pulls the outcome toward it, even when the number is arbitrary. If you leave the Valuation blank, the investor sets the anchor, and the anchor is set low because the investor is screening for loss. Assume an investor opens at ₹28 crore pre-money and the negotiation settles near ₹30 crore. Assume a founder with a supported ask of ₹45 crore settles near ₹44 crore. On the same ₹8 crore round:
| Scenario | Pre-Money Valuation | Post-Money | Investor Stake |
|---|---|---|---|
| Blank ask, investor anchors | ₹30 crore | ₹38 crore | 21.1% |
| Supported ask, founder anchors | ₹44 crore | ₹52 crore | 15.4% |
| Difference | ₹14 crore | ₹14 crore | 5.7 percentage points |
Illustrative negotiation outcomes. Investor stake = round size ÷ post-money Valuation.
Five point seven percentage points is worth ₹22.7 crore at a hypothetical ₹400 crore exit, ignoring later dilution. The founder did not need a better business to capture it. The founder needed a number with a basis.
Why an Unsupported Ask Fails: The Reverse DCF
Now take Version B, the ₹90 crore ask. Investors test it by asking what must be true. Using a simple discounted cash flow for a company with ARR of ₹9 crore, with free cash flow of (₹3 crore), ₹1 crore, ₹6 crore, ₹14 crore and ₹26 crore over five years, a 30% discount rate suitable for this stage, and 5% terminal growth, the enterprise value is about ₹42.3 crore. Here is how that moves with the two key assumptions.
| Discount Rate | Terminal Growth 4% | Terminal Growth 5% | Terminal Growth 6% |
|---|---|---|---|
| 25% | ₹57.8 crore | ₹60.3 crore | ₹63.1 crore |
| 30% | ₹40.9 crore | ₹42.3 crore | ₹43.8 crore |
| 35% | ₹30.2 crore | ₹31.1 crore | ₹32.0 crore |
Enterprise value in ₹ crore, ignoring net debt. Cash flows and rates are illustrative inputs.
To justify ₹90 crore at a 30% discount rate and 5% terminal growth, every cash flow would need to be about 2.1x higher (₹90 crore ÷ ₹42.3 crore), taking year-5 free cash flow to roughly ₹55 crore against ₹26 crore in the base case. An investor reaching that conclusion does not counter at ₹60 crore. The investor concludes the founder does not understand the business's economics and moves on.
The Triangulated Ask That Survives
| Method | Basis | Indicated Range |
|---|---|---|
| Revenue multiple | ARR ₹9 crore × 4.5x to 6x, benchmarked to comparable rounds | ₹40.5 crore to ₹54 crore |
| DCF, base case | 30% discount rate, 5% terminal growth | ₹42.3 crore (₹30.2 crore to ₹63.1 crore across the sensitivity grid) |
| Defensible ask | Where the methods overlap | ₹40 crore to ₹50 crore, anchored at ₹45 crore |
⚠️ The Ask on Your Slide Must Later Pass a Statutory Test. A preferential allotment under Section 62(1)(c) of the Companies Act, 2013, read with Rule 13(2)(g) of the Share Capital Rules, needs a Registered Valuer report supporting the issue price. An issue to a non-resident must meet the fair value floor in Rule 21 of the FEMA NDI Rules, 2019, certified by a Chartered Accountant, SEBI-registered merchant banker or cost accountant, and reported on Form FC-GPR within 30 days of allotment. The draft FEMA (Foreign Investment) Rules, 2026 are still in draft, so the NDI Rules continue to apply. Angel tax under Section 56(2)(viib) was abolished from 1 April 2025, which removes a tax ceiling on your pricing but not these requirements. See Section 62 preferential allotment Valuation and when Valuation is mandatory in India.
📌 What This Mistake Costs You
- Blank ask: 5.7 points of ownership, worth ₹22.7 crore at a ₹400 crore exit
- Unsupported ask: a failed process (₹1.2 crore of runway) and a reputation as a founder who does not know the numbers
- Unchecked compliance path: a repricing at closing, when your negotiating leverage is lowest
Mistake 4: Claiming "We Have No Direct Competitors"
Competitive Credibility
📌 Bad Pitch Deck Example: The Slide
"Competition: None. We are the only platform that combines X, Y and Z."
An investor reads this sentence in one of two ways. Either the founder has not researched the market, or there is no market. Both are disqualifying, and the investor can test which one applies in about ten minutes with a search engine, the public filings of private competitors on the MCA portal, and one phone call to a customer.
Competition Is the Customer's Current Solution
Customers who need a problem solved are already solving it. The question is how. Your real competition is whatever the customer does today, and for most Indian B2B startups that is a spreadsheet and two employees. Showing that alternative, priced, is far stronger than claiming it does not exist.
| Alternative | What the Customer Does Today | Annual Cost to the Customer |
|---|---|---|
| Status quo | Spreadsheets, 2 full-time staff (₹4.2 lakh each) and error correction (₹2.4 lakh) | ₹10.8 lakh |
| ERP module | Add-on inside the existing ERP, partial workflow coverage | Varies; bundled |
| Point-solution SaaS | One or two narrow tools stitched together | Illustrative ₹3 lakh to ₹4 lakh, with manual gaps |
| Your product | Single platform covering the full workflow | ₹6 lakh (55.6% of the status quo cost) |
Illustrative customer economics. Replace with your own customer research.
The slide now says something an investor can use: the customer pays ₹10.8 lakh to do nothing new, and your product costs 55.6% of that while covering the full workflow. That is a competitive position. "No competitors" is not.
The Credibility Arithmetic
An investor evaluates a deck on a handful of key claims: market, traction, margins, retention and competition. Suppose the investor treats each as 90% likely to be true. All five holding together has a probability of 0.95, or 59.0%. Now the investor finds three competitors in ten minutes. The competition claim is false, and the investor revises every other claim down, because a founder who misstates one fact may have misstated others. At 70% each, the chance that all five hold is 0.75, or 16.8%.
📌 What This Mistake Costs You
- Overall deck credibility falls from 59.0% to 16.8%, a loss of 42 points, from one sentence
- The loss spreads: market size, margins and traction slides are all re-read with suspicion
- The correct version costs nothing: name three alternatives, price the status quo, and state why you win
Want Your Valuation Ask and Cap Table Stress-Tested?
We triangulate your Valuation range, model the post-round cap table including the option pool, and check the round against Section 62(1)(c) and FEMA Rule 21 before you name a number.
Mistake 5: A Bloated Cap Table Before the Round Even Starts
Deal Structure
📌 Bad Pitch Deck Example: The Cap Table Slide
Founders A and B: 52%. Departed co-founder: 12%. Seven angels: 16%. Three advisors: 7%. Seed investor: 8%. ESOP pool: 5%.
The table sums to 100% and looks harmless. An investor sees five separate problems: a former co-founder holding 12% for no ongoing work, advisors with equity and no vesting, 14 separate parties who must sign the shareholders' agreement, an option pool too small to hire with, and founders whose stake will fall sharply once the round closes.
The Option Pool Shuffle: What the Headline Pre-Money Hides
Investors commonly require the post-money option pool to reach a target, often 10%, and create it before the round, so that the dilution falls on existing holders. Take an ₹8 crore round at a ₹40 crore headline pre-money (₹48 crore post-money, so the new investor holds 16.7%) with a 10% post-money pool.
- The existing 95% of non-pool holders must fit into what is left after the investor (16.7%) and the pool (10.0%): 73.3% of the company
- Total post-round shares = 95 ÷ 73.3% = 129.5 units, where the pre-round table totals 100 units
- The new pool is 10% of 129.5 = 12.95 units, so 7.95 new pool units are created, which is 6.14% of the post-money company
- That top-up is worth 6.14% × ₹48 crore = ₹2.95 crore, so the effective pre-money is ₹40 crore minus ₹2.95 crore, or ₹37.05 crore
Without the pool top-up, the founders' 52% would fall to 43.3% (52% × 40 ÷ 48). With it, they fall to 40.1%, a further 3.2 points that the headline never mentions. At a ₹400 crore exit that is ₹12.8 crore.
Dead Equity and Unvested Advisors: The Cleanable Part
The pool top-up is a negotiation. Dead equity and unvested advisor grants are a choice. Compare the same round for the messy table and for a cleaned table in which the departed co-founder's holding is negotiated from 12% down to 4%, and the advisors' from 7% to 3% with proper vesting.
| Holder | Pre-Round (Messy) | Post-Round (Messy) | Pre-Round (Cleaned) | Post-Round (Cleaned) |
|---|---|---|---|---|
| Founders A and B | 52.0% | 40.1% | 59.1% | 45.9% |
| Departed co-founder | 12.0% | 9.3% | 4.5% | 3.5% |
| Seven angels | 16.0% | 12.4% | 18.2% | 14.1% |
| Three advisors | 7.0% | 5.4% | 3.4% | 2.7% |
| Seed investor | 8.0% | 6.2% | 9.1% | 7.1% |
| ESOP pool | 5.0% | 10.0% | 5.7% | 10.0% |
| New investor | 0% | 16.7% | 0% | 16.7% |
Figures rounded to one decimal place, so columns may not sum to exactly 100%. Same ₹8 crore round at ₹40 crore pre-money with a 10% post-money pool in both cases.
Cleaning the table lifts the founders' post-round holding from 40.1% to 45.9%, a gain of 5.8 points, worth ₹23.2 crore at a ₹400 crore exit. Cleaning also reduces the number of signatories and the number of people with consent rights, which shortens the definitive documentation stage.
📋 The Statutory Records an Investor Will Compare Against Your Slide
- PAS-3: the return of allotment is due within 30 days of each allotment, and every issue shown on your cap table should have one
- MGT-7: the annual return lists shareholders, and it must match the cap table
- ESOP approval: the pool must be backed by a special resolution under Section 62(1)(b) of the Companies Act, 2013, and the pool shown must match the resolution
- Foreign holders: any non-resident angel requires FEMA compliance and an FC-GPR filing, which investors check at diligence
- See ESOP structuring and pool sizing for how to set the pool before the round
📌 What This Mistake Costs You
- Pool shuffle: effective pre-money of ₹37.05 crore instead of ₹40 crore, and 3.2 points of founder ownership
- Dead equity and unvested advisors: a further 5.8 points, worth ₹23.2 crore at a ₹400 crore exit
- Friction: 14 signatories to a shareholders' agreement, and a weakened founder incentive that investors price in
How to Pressure-Test Your Deck Before Sending It Out
Pre-Send Phase
Every mistake above can be caught with a test you can run in an afternoon. The six tests below mirror what the investor does, in the order the investor does it.
1. Run the 90-Second Skim
Read only the headline of each slide in 90 seconds. If the story, the ask and the metric that matters are not clear from headlines alone, the deck will lose investors who give you 15 seconds a slide.
2. Recompute Unit Economics From the P&L
Rebuild CAC with sales salaries and marketing programmes, gross margin after support and cloud costs, and churn including paused and downgraded accounts. Show the investor's version on the slide.
3. Build the Market Bottom-Up and Test for Venture Scale
Multiply target accounts by ACV by share. Then run the return test: exit value needed for a 10x return, ARR needed at your multiple, and whether your expansion path reaches it.
4. Triangulate the Valuation and Ask "What Must Be True"
Use a revenue multiple, a DCF with a sensitivity grid and precedent rounds. Pick an ask inside the overlap, and test any higher number by asking how much larger every cash flow would have to be.
5. Search for Competitors for Ten Minutes
Name three real alternatives, including the status quo, price each, and state why customers switch. If a ten-minute search finds one you did not list, the slide is not ready.
6. Model the Post-Round Cap Table
Include the option pool top-up, every convertible and every advisor grant. Know your effective pre-money and your post-round founder holding before an investor calculates them.
| Test | Pass Mark |
|---|---|
| Skim test | Story and ask are clear from headlines alone |
| Unit economics | Fully loaded LTV to CAC of about 3x or higher and payback of about 18 months or less (benchmarks commonly used by SaaS investors) |
| Market | A bottom-up path to the ARR an investor needs to return the cheque |
| Valuation | Methods overlap and the ask sits inside the overlap |
| Competition | Real alternatives named, with the status quo cost shown |
| Cap table | Effective pre-money known, no dead equity, founders retain a motivating stake |
| Reconciliation | Deck revenue bridges to GSTR-3B turnover and audited accounts |
📋 Pre-Send Checklist for Indian Rounds
- Revenue on the deck reconciled to GSTR-1, GSTR-3B and audited financials
- Cap table matched to MGT-7 and PAS-3 filings
- Board and shareholder resolutions ready for the issue, including the special resolution under Section 62(1)(c) where applicable
- Registered Valuer report path confirmed under Rule 13(2)(g) of the Share Capital Rules
- FEMA Rule 21 pricing floor and FC-GPR filing path confirmed for any foreign investor
- A second reader, ideally a CA or finance professional, who has tried to break the deck
Ready to Pressure-Test Your Deck Before Investors Do?
We run all six tests on your deck and model, reconcile it to your books, and give you a written list of what to fix before outreach.
Pitch Deck vs. Business Plan: What Is the Difference and Which Do Investors Want?
Fundamentals
Founders new to fundraising often prepare a business plan when investors ask for a deck, or send a deck when a bank asks for a plan. They are different documents with different readers. A pitch deck persuades an investor to take a meeting. A business plan describes how the company will operate, and is read by lenders, partners and the management team.
| Dimension | Pitch Deck | Business Plan |
|---|---|---|
| Primary purpose | Win a first meeting and a term sheet | Document strategy, operations and finances in detail |
| Typical length | 12 to 15 core slides plus an appendix | 20 to 40 pages |
| Main reader | Venture investors, angels, family offices | Banks, strategic partners, internal teams, some grant bodies |
| Financials | Summary metrics and a model available on request | Detailed multi-year projections, often in lender formats such as CMA data |
| Reading time | 2 to 4 minutes on first pass | 30 minutes or more |
| Update frequency | Every fundraising round, per investor type | Annually or at major strategic change |
| Where the mistakes in this article apply | Directly, since every slide is a screening point | Partly, since a lender also tests projections and unit economics |
Investors increasingly ask for three things in sequence: the deck first, then a financial model, then a data room. A full business plan is rarely the first document requested. Founders should prepare the deck and the model together, because the model is where the numbers on every slide must trace back to. If you are still deciding how much of this to build yourself, our guide on whether to hire pitch deck experts or build it in-house covers the economics.
📁 A Recent Engagement
B2B Payroll Compliance Software
₹6.2 Cr ARR
₹7 Cr Round
A founder came to us after 22 investor conversations produced two second meetings. The deck sized the market as 1% of a ₹50,000 crore HR technology market (₹500 crore), showed an LTV to CAC of 8.4x, asked for a pre-money "to be discussed", and carried a cap table with 11 holders including a departed co-founder at 9%.
Our review found three problems. The bottom-up market at today's pricing supported ₹38 crore of ARR in year five, with a credible path to ₹110 crore through added modules. Fully loaded CAC (including ₹36 lakh of quarterly sales salaries the deck had excluded) brought LTV to CAC down to 2.9x. The pool top-up and dead equity left the founders at 41% after the planned round.
We rebuilt the market slide bottom-up with the expansion path, restated unit economics on a fully loaded basis, triangulated a pre-money range of ₹30 crore to ₹36 crore, and restructured the departed co-founder's holding and the advisor vesting before outreach. Of the next 15 investor conversations, 6 reached a second meeting, and the company closed ₹7 crore at ₹33 crore pre-money, a 5.3x multiple on ARR, with the investor taking 17.5%. Details have been changed and figures rounded.
More Pitch Deck Mistakes and Red Flags Investors Spot in Seconds
1. Hockey-stick projections with no drivers
Revenue triples every year for three years while headcount, CAC and pricing stay flat.
CONSEQUENCE
The investor discards your forecast and builds their own, usually at a lower growth rate, which pulls the Valuation down with it.
FIX
Build a driver-based model where growth comes from customers, ACV and churn, and show the assumptions.
2. Use of funds with no runway or milestone
A pie chart shows percentages of the raise but not what the money achieves.
CONSEQUENCE
The investor cannot see whether ₹8 crore reaches the next round, so every follow-up email asks the same question.
FIX
State the months of runway and the specific metrics you will reach before the next raise.
3. Vanity metrics instead of revenue and retention
Downloads, registered users and GMV feel like traction because the numbers are large.
CONSEQUENCE
GMV of ₹50 crore at a 4% take rate is ₹2 crore of revenue, and the investor does that arithmetic in seconds.
FIX
Lead with net revenue, paying customers, cohort retention and contribution margin.
4. Traction that does not reconcile to the books
Revenue on the slide comes from the MIS, but nobody has compared it with GSTR-3B turnover or audited accounts.
CONSEQUENCE
An unexplained variance becomes a diligence flag, and one flag makes the investor re-check every other number.
FIX
Reconcile deck revenue to GSTR-3B and audited accounts before sending, and show the bridge.
5. Ignoring the regulatory path for the round
The price and instrument are chosen commercially, with no check against Section 62(1)(c) or FEMA Rule 21.
CONSEQUENCE
A price below the Rule 21 fair value floor cannot be allotted to a non-resident investor, which forces a repricing at closing.
FIX
Check the compliance path, including the Registered Valuer report and the FC-GPR timeline, before the term sheet.
Closing Summary: Every Pitch Deck Mistake Is a Number an Investor Will Recompute
The five biggest pitch deck mistakes share a single root cause: a claim on a slide that the numbers behind it cannot carry. Top-down market sizing fails the venture-scale test. Hidden unit economics collapse from 11.7x to 2.7x when fully loaded. A missing Valuation basis hands the anchor, and 5.7 points of ownership, to the investor. "No direct competitors" turns 59% credibility into 17%. A bloated cap table turns a ₹40 crore headline into ₹37.05 crore and costs founders another 5.8 points after the round. Investors weigh each of these as a loss, and a loss outweighs any growth chart. The remedy is to recompute everything before they do. At Elite Valuation, we build and test decks the way investors read them: from the model outward, with every number traceable, every ask supported, and every round compliant before the term sheet is signed.
Find the Mistakes Before an Investor Does
Numbers reconciliation → Unit economics rebuild → Valuation range → Cap table model → Compliance readiness. One engagement, built to survive the first 15 seconds of every slide.
FAQ: How Long Does It Take an Expert to Build a Deck From Scratch?
CA Sagar Shah, Founder
Mr Sagar Shah is the Founder of Elite Valuation and leads the firm’s Valuation and Advisory practice. With over 15+ years of professional experience.
Published Insights