Part of our ESOP in India knowledge cluster. This guide focuses on the rollout and operating process after a company decides to create an ESOP. For the wider framework covering scheme design, eligibility, Valuation, tax and strategy, see our complete ESOP in India guide.
Creating an Employee Stock Option Plan is relatively easy on paper. Implementing it properly is considerably more involved. A company may decide that 8% or 10% of its equity should be reserved for employees, prepare an ESOP scheme and obtain the required approvals. But unless the company also establishes a grant process, Valuation framework, vesting records, exercise workflow, tax mechanism, accounting process and statutory record trail, the scheme can remain little more than a legal document.
This is where ESOP implementation services in India become important. Implementation converts the commercial intent behind an ESOP into an operational system that can withstand employee questions, investor due diligence, audits, tax review and future fundraising or M&A. For startups and unlisted companies, implementation often requires coordinated inputs from management, the company secretary, finance and payroll teams, tax advisors, Valuation specialists and, at specific stages, a SEBI-registered Category I Merchant Banker.
At Elite Valuation, the implementation approach is therefore not limited to drafting a scheme. The objective is to build a complete chain from pool creation → approvals → grant → vesting → exercise → tax → allotment → reporting, with a clear responsibility matrix and documentary trail at each stage.
Key Takeaways:
- Implementation begins before the first grant. Pool sizing, eligibility, dilution, exercise-price strategy and approval sequencing should be resolved first.
- Section 62(1)(b) and Rule 12 form the core Companies Act framework for employee stock options by unlisted Indian companies.
- Grant, vesting, exercise and allotment are separate events and should be tracked separately for every employee.
- ESOP Valuation is purpose-specific. Underlying share Valuation, option fair value for accounting and exercise-stage tax FMV are not interchangeable.
- An IBBI Registered Valuer can support relevant equity or business Valuation requirements, while exercise-stage tax FMV for unlisted shares requires the prescribed Merchant Banker route.
- Form SH-6 and an internal grant tracker should remain aligned with the cap table and allotment records.
- Choose the operating route before rollout. The ESOP direct route is usually simpler, while an ESOP Trust route can add flexibility but also brings a separate trust, funding, Valuation and governance layer.
What Are ESOP Implementation Services?
ESOP implementation services cover the practical steps required to convert an approved employee ownership strategy into a functioning employee stock option programme. The process begins with the commercial architecture of the plan and continues through legal documentation, approvals, grants, vesting, exercise, taxation, allotment and ongoing administration.
Featured Snippet — ESOP Rollout Process
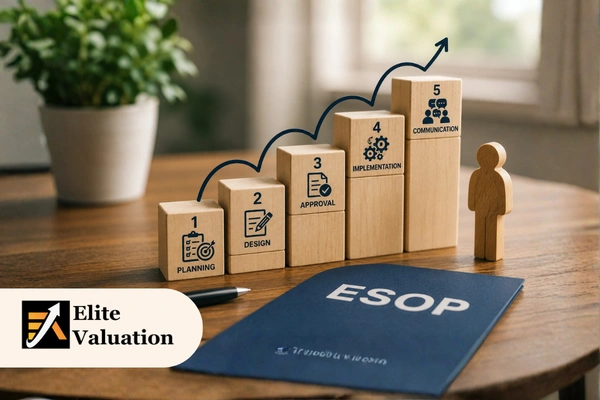
A complete ESOP rollout generally follows eight stages: 1. Strategy and pool sizing → 2. Scheme drafting → 3. Corporate approvals → 4. Valuation and accounting setup → 5. Employee grants → 6. Vesting administration → 7. Exercise and taxation → 8. Share allotment and ongoing compliance.
Implementation is different from scheme drafting. The scheme establishes the legal and commercial rules. Implementation ensures that those rules are actually followed for each employee. If a scheme states that options vest over four years, implementation determines who tracks that four-year schedule, how resignations are processed, when exercise notices are accepted, how tax is collected and when shares are allotted.
Why Does ESOP Rollout Need a Defined Process?
Most ESOP problems do not arise because the company has no scheme. They arise because the scheme, cap table, employee communication and actual operating practice drift apart. A founder may verbally promise “1% equity” while the approved scheme is expressed as a fixed number of options. HR may describe a four-year vesting schedule while a grant letter contains different terms. Finance may model dilution on issued share capital while investors calculate it on a fully diluted basis.
Implementation Risk — Inconsistent ESOP Records
If the Board records, grant letters, cap table, SH-6 register and employee statements show different numbers, the issue usually surfaces during fundraising, audit or due diligence — when the cost of correcting historical records is significantly higher.
A well-defined rollout creates a single operating record for the pool, employee grants, vesting, exercise, tax and allotment. This becomes especially important when the company starts making multiple grant cycles or has employees leaving and joining between funding rounds.
| Area | What Must Be Controlled |
|---|---|
| ESOP pool | Approved, granted, vested, exercised, lapsed and available options |
| Employee grants | Grant date, number of options, exercise price and conditions |
| Vesting | Time-based, milestone-based and performance conditions |
| Exercise | Window, exercise notice, payment and tax collection |
| Leavers | Vested and unvested treatment on resignation or termination |
| Valuation | Correct report for the correct regulatory or accounting purpose |
| Cap table | Fully diluted ownership before and after exercises |
| Statutory records | Approvals, register, allotments and applicable filings |
Which Laws Govern ESOP Implementation in India?
For an unlisted Indian company, the core corporate-law framework is Section 62(1)(b) of the Companies Act, 2013 read with Rule 12 of the Companies (Share Capital and Debentures) Rules, 2014. These provisions govern the employee stock option scheme, shareholder approval framework, eligibility conditions, disclosures, vesting, exercise and maintenance of the prescribed ESOP register.
Where the company is listed, the implementation framework is supplemented by the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021. Where employees are resident outside India, FEMA and the applicable foreign investment framework must also be considered. For companies applying Ind AS, share-based payment accounting is governed by Ind AS 102. Employee taxation at exercise is governed by the applicable Income-tax framework and prescribed FMV rules.
Implementation Principle — One ESOP, Multiple Frameworks
An ESOP may be one employee incentive programme, but its rollout can simultaneously touch corporate law, accounting, payroll tax, Valuation, foreign exchange law and cap-table governance. The implementation plan should therefore identify the responsible professional for each workstream instead of expecting one report or one advisor to satisfy every requirement.
Promoter Eligibility for ESOP — DPIIT Startup Exception
Rule 12 ordinarily excludes an employee who is a promoter or belongs to the promoter group, and also excludes a director who directly or indirectly holds more than 10% of the outstanding equity shares through himself, a relative or a body corporate. For a startup company covered by the applicable DPIIT notification, these two exclusions do not apply for up to 10 years from the date of incorporation or registration. Accordingly, a DPIIT recognized startup ESOP can, during the permitted window, include eligible promoter-employees or qualifying promoter-directors, subject to the remaining scheme and approval requirements.
Important distinction: the Companies Act startup relaxation for promoter eligibility should not be confused with the separate Income-tax conditions for an eligible startup referred to in Section 80-IAC. DPIIT recognition by itself does not automatically establish eligibility for every startup tax benefit.
How Should the ESOP Pool and Eligibility Be Set?
Before drafting the scheme, management should answer a commercial question: how much equity is the company genuinely willing to dilute? Pool size should not be decided only by copying a market percentage. The company should model the current cap table, outstanding convertibles, proposed fundraising, strategic hiring plan and expected employee grants on a fully diluted basis.
Eligibility should then reflect both the legal definition of eligible employees and the company's retention strategy. The company should determine whether the plan is intended mainly for CXOs and senior management, for critical technical talent, for a wider managerial population or for strategic hires that may join over the next 12–24 months.
| Employee Category | Illustrative Allocation from 10,000 Options |
|---|---|
| CXO / leadership | 4,000 |
| Functional heads | 2,500 |
| High-potential managers | 2,000 |
| Strategic-hire reserve | 1,500 |
| Total | 10,000 |
This is only an illustration. The important implementation point is that the company should know why options are being reserved and how long the pool is expected to support hiring and retention before the next shareholder approval.
How Is the ESOP Scheme Drafted and Approved?
Once commercial terms are settled, they should be converted into an enforceable scheme. A robust ESOP scheme normally addresses the total pool, eligible employees, grant authority, vesting conditions, exercise price, exercise period, treatment of leavers, death or permanent incapacity, corporate actions, lapse and cancellation, liquidity events and the power to amend the scheme.
1. Freeze the Commercial Term Sheet
Finalise pool size, eligibility, vesting, exercise price framework, exercise window and leaver treatment before documentation begins.
2. Draft the ESOP Scheme
Translate the commercial decisions into a complete scheme aligned with the Companies Act framework and the company's constitutional documents.
3. Obtain Board Approval
Place the proposed scheme, shareholder notice and implementation authority before the Board and record the approval trail.
4. Complete Shareholder Approval
Obtain the applicable shareholder approval under Section 62(1)(b) read with Rule 12 and complete related secretarial actions.
5. Open the Operating Records
Create the ESOP register, internal grant tracker, cap-table reconciliation and standard grant documentation before the first employee grant.
Approval Check — Investor and Articles Restrictions
The statutory approval is only one part of the rollout. The company should also review its Articles of Association, shareholders' agreement, reserved-matter list and investor consent rights before creating or expanding an ESOP pool.
Should You Choose the ESOP Direct or Trust Route?
An ESOP can be implemented through an ESOP direct route or, where the structure and objectives justify it, through an ESOP Trust route. The choice affects how shares are held, when dilution occurs, how employee exercises are settled and how much administration is required after the scheme is launched.
| Implementation Point | ESOP Direct Route | ESOP Trust Route |
|---|---|---|
| How shares reach employees | The company generally allots shares directly to the employee when vested options are exercised. | A separate employee benefit trust acquires, subscribes to or holds shares and transfers the relevant shares to employees in accordance with the scheme. |
| Administrative structure | Usually simpler for closely held and startup companies because no separate trust administration is required. | Requires a trust structure, trustees, trust records, banking, accounting and a separate reconciliation between trust holdings and employee entitlements. |
| Dilution / share availability | Fresh dilution generally arises when the company issues shares on exercise. | The trust may hold shares in advance, subject to the legal route used for acquisition or subscription and the applicable funding restrictions. |
| Company funding of trust | Not applicable because the employee deals directly with the company for exercise and allotment. | If the company provides money for purchase or subscription of shares by trustees for employee benefit, Section 67 read with Rule 16 becomes relevant. The framework includes shareholder approval and, for unlisted shares, Registered Valuer requirements for the relevant purchase Valuation, along with the prescribed funding limit. |
| Best suited for | Companies seeking a comparatively lean grant-to-allotment process. | Companies that have a specific reason to warehouse shares, manage secondary acquisitions or operate employee benefits through a dedicated trust structure. |
Implementation Decision — Do Not Choose the Trust Route by Default
The ESOP Trust route can be useful, but it is not simply a more sophisticated version of the direct route. It adds a separate legal and operating layer. For an unlisted company, Rule 16 should be reviewed where the company funds the trust; if shares are purchased by the trust in an unlisted company, the purchase Valuation must be made by a Registered Valuer. Listed-company trusts are additionally governed by the applicable SEBI share-based employee benefit framework.
How Should ESOP Valuation Be Planned?
One of the most common implementation errors is treating ESOP Valuation as a single number. The company may actually face different Valuation questions at different stages, and the answer to each question can require a different methodology, date and professional credential.
Featured Snippet — Three Valuation Questions
Underlying equity Valuation answers what the company's shares are worth. Option fair value supports share-based payment accounting where applicable. Exercise-stage FMV supports employee perquisite taxation. These exercises should be scoped separately.
| Valuation Question | Typical Purpose | Implementation Focus |
|---|---|---|
| Underlying share / equity value | Commercial decision-making, governance or other applicable Valuation purposes | Business position, capital structure, share rights and Valuation date |
| Option fair value | Share-based payment accounting where applicable | Share value, exercise price, expected life, volatility, risk-free rate and dividend assumptions |
| Exercise-stage FMV | Employee perquisite taxation | Prescribed Income-tax method and the required Merchant Banker process for unlisted equity shares |
An IBBI Registered Valuer — Securities or Financial Assets can support relevant independent business or equity Valuation requirements. However, an IBBI Registered Valuer report should not automatically be reused as the exercise-stage tax certificate simply because both reports contain a share value. The implementation file should clearly identify the purpose of each Valuation and the rule under which it is being obtained.
Need Help Implementing an ESOP?
Build the scheme, Valuation and rollout process on one coordinated implementation timeline.
How Are Employee Grants Issued and Documented?
Scheme approval and employee grant are different events. Shareholders may approve a pool of 1,00,000 options, while the Board or authorised committee may initially grant only a portion of that pool. Each grant should therefore be separately approved, documented and entered into the ESOP tracking system.
| Grant Term | Illustrative Entry |
|---|---|
| Grant date | 1 September 2026 |
| Number of options | 4,000 |
| Exercise price | Rs. 100 per option |
| Vesting commencement | 1 September 2026 |
| Vesting schedule | 25% annually over four years |
| Exercise period | As specified in the approved scheme |
| Exit / leaver treatment | As specified in the scheme and grant letter |
The employee communication should clearly explain that an option is not a share on the grant date. It is a contractual right to acquire a share later if the vesting and exercise conditions are satisfied. This distinction helps avoid confusion around immediate ownership, voting rights, dividends and liquidity.
How Do Vesting, Exercise and Allotment Work?
A disciplined implementation distinguishes four separate events: grant, vesting, exercise and allotment. Grant creates the employee's option entitlement. Vesting makes the relevant portion eligible for exercise after the applicable conditions are satisfied. Exercise occurs when the employee elects to acquire shares and pays the exercise price together with applicable tax requirements. Allotment is the corporate action through which the company actually issues shares.
1. GRANT
2. VESTING
Right becomes exercisable
3. EXERCISE
Employee pays price / tax
4.ALLOTMENT
Shares are issued
For an unlisted-company ESOP governed by Rule 12, there is generally a minimum one-year period between grant and vesting. Companies may use cliff, graded or milestone-based structures beyond that minimum framework, provided the approved scheme terms are followed consistently.
Practical Illustration — Exercise and Tax Workflow
4,000 Options with 25% Annual Vesting
Assume an employee receives 4,000 options at an exercise price of Rs. 100. After the first year, 1,000 options vest and the employee exercises 500 options. The exercise-price payment is therefore Rs. 50,000. If the applicable exercise-stage FMV is Rs. 400 per share, the simplified perquisite spread is Rs. 300 per share, or Rs. 1,50,000 for 500 shares. Payroll, tax collection, exercise acceptance and allotment should all be coordinated before shares are issued.
What Records and Filings Should Be Maintained?
The implementation does not end when employees receive their grant letters. The company should maintain a continuing statutory and operational record of the scheme. Form SH-6 — Register of Employee Stock Options is the prescribed register under Rule 12, and the internal cap-table and grant records should reconcile to it.
| Event | Typical Record / Action |
|---|---|
| Scheme adoption | Board and shareholder approval records |
| Grant | Grant approval, grant letter / option agreement and SH-6 update |
| Vesting | Updated vesting schedule and employee-level entitlement |
| Leaver event | Lapse / exercisable balance determination and tracker update |
| Exercise | Exercise notice, exercise-price payment and tax documentation |
| Share allotment | Board action, applicable return of allotment and cap-table update |
| Ongoing administration | SH-6, Board's Report disclosures where applicable and periodic pool reconciliation |
As the number of grants increases, ESOP management software can help digitise employee-level grant records, vesting calculations, exercise notices, lapse tracking, employee statements and fully diluted cap-table reconciliation. The software should support the compliance process rather than replace it: the statutory SH-6 register, Board / committee approvals, grant documentation and allotment records must still be maintained in the form required under the applicable law.
Control Formula — ESOP Pool Reconciliation
Approved Pool − Outstanding Grants − Options Exercised − Options Reserved / Committed + Options Lapsed or Cancelled = Options Available for Future Grant. The exact tracker can be structured differently, but every company should be able to reconcile its legal pool to its fully diluted cap table.
How Are ESOP Accounting and Tax Set Up?
The finance team should be involved before the first grant rather than at year-end. Where Ind AS 102 applies, share-based payment accounting requires the company to measure and recognise the relevant employee compensation cost in accordance with the standard. The implementation tracker should therefore preserve the grant date, option quantity, vesting schedule, fair value, forfeitures, modifications, cancellations, vested options and exercises.
Employee taxation operates on a different basis. At exercise, the taxable perquisite is linked to the applicable FMV and the amount paid by the employee. For unlisted equity shares, the exercise-stage FMV is determined through the prescribed Merchant Banker framework. The payroll team should know the expected exercise window in advance so that the FMV process and tax collection do not delay allotment.
Deferred Taxation for Startup ESOPs — Section 80-IAC Link
For employees of an eligible startup referred to in Section 80-IAC, the ESOP perquisite continues to be computed and reported for the year in which the shares are allotted, but the timing of TDS / tax payment is deferred. The eligible startup is required to deduct the tax within 14 days from the earliest of: (i) expiry of 48 months from the end of the assessment year in which the shares are allotted, (ii) the date on which the employee ceases to be employed by the startup, or (iii) the date on which the employee sells the allotted shares.
This deferred taxation for startup ESOPs can reduce the immediate cash-flow pressure that would otherwise arise where an employee has a taxable ESOP perquisite without liquidity from a share sale. However, the relief applies to an eligible startup under the Section 80-IAC framework; it should not be assumed merely because the company has DPIIT recognition.
Common Error — Using One Valuation for Every Purpose
A business Valuation, an option fair-value model and a tax FMV certificate may all refer to the same ESOP, but they answer different questions. Reusing one report without checking its governing purpose can create compliance, accounting and employee-tax issues.
How Do Cross-Border and Listed ESOPs Differ?
A standard Indian unlisted-company checklist should not be copied mechanically where employees are located outside India or the company is listed. For non-resident employees, the company should evaluate the FEMA framework, employee residency, sectoral limits, approval-route conditions and applicable reporting. These issues are best identified before grant so that the exercise and allotment stage does not reveal an avoidable foreign exchange problem.
For listed companies, the SEBI (Share Based Employee Benefits and Sweat Equity) Regulations, 2021 introduce a more detailed governance and disclosure framework. Depending on the structure, implementation can involve the compensation committee, stock exchanges, trustees, depositories and additional reporting. Accordingly, a listed-company rollout should use a separate project plan rather than adapting an unlisted-company template.
For a deeper discussion of foreign employees and overseas parent-company plans, see our cross-border ESOP India guide complete ESOP in India guide. For scheme architecture and vesting choices, see our ESOP scheme design guide for startups.
What Should an ESOP Implementation Partner Deliver?
A professional ESOP implementation engagement should not conclude with a PDF copy of the scheme. The objective should be to establish a repeatable process that the company can continue operating after launch, with clear ownership of every task.
| Workstream | Typical Deliverable |
|---|---|
| ESOP strategy | Pool sizing and fully diluted dilution model |
| Scheme design | Commercial term sheet and implementation decisions |
| Documentation | Draft ESOP scheme and grant-document framework |
| Approval support | Board / shareholder documentation inputs and approval roadmap |
| Equity Valuation | Applicable independent Valuation support |
| Accounting Valuation | Option fair-value working where required |
| Administration | Grant, vesting, lapse and exercise tracker |
| ESOP technology | ESOP management software setup, employee records and cap-table / SH-6 reconciliation workflow |
| Exercise and tax | Exercise workflow and Merchant Banker FMV coordination |
| Allotment | Cap-table and compliance coordination |
| Employee communication | Grant explanation and employee FAQ / briefing material |
An IBBI Registered Valuer becomes particularly useful where management wants the ESOP economics to be supported by an independent understanding of the company's equity value rather than selecting an exercise price or communicating employee wealth creation without a defensible Valuation framework. The strongest implementation model brings management, company secretarial, finance, tax, Valuation and payroll workstreams onto one coordinated timeline.
Closing Summary: From Scheme to Share Allotment
An ESOP becomes effective only when the company can move consistently from scheme design to grant, vesting, exercise, taxation and share allotment. The scheme document is therefore the foundation, not the finish line. Companies should establish the pool on a fully diluted basis, decide whether the ESOP direct route or ESOP Trust route is appropriate, test employee and promoter eligibility, obtain the correct approvals, document each employee grant, maintain vesting and lapse records, perform the appropriate Valuation for each purpose, integrate employee taxation with payroll and maintain the prescribed statutory and cap-table records. The Valuation work requires particular care because underlying equity Valuation, option fair value for accounting and exercise-stage tax FMV may have different objectives and professional requirements. Elite Valuation supports companies in building this coordinated implementation framework so the ESOP remains employee-ready, audit-ready and transaction-ready throughout its life.
Planning to Roll Out an ESOP?
Coordinate pool design, Valuation, grants, vesting, exercise and compliance through one implementation roadmap.
Frequently Asked Questions — ESOP Implementation
CA Sagar Shah, Founder
Mr Sagar Shah is the Founder of Elite Valuation and leads the firm’s Valuation and Advisory practice. With over 15+ years of professional experience.