Acquiring a business is among the highest-stakes decisions a company, promoter, or investor can make. The upside — accelerated growth, market access, technology acquisition, vertical integration — is significant. But with over 70% of acquisitions globally estimated to fail to deliver projected returns, the process by which you identify, evaluate, and execute the acquisition is the single largest determinant of success or failure.
In India's regulatory environment, the buy-side M&A process carries additional layers of complexity — FEMA compliance for cross-border elements, Competition Commission of India (CCI) approval thresholds, SEBI requirements for listed targets, Companies Act compliance for schemes of arrangement, and Income Tax implications on deal structuring. Each of these regulatory touchpoints can accelerate or delay your transaction by months if not handled correctly from the outset.
At Elite Valuation, we act as the valuation, due diligence, and transaction advisory partner on buy-side M&A mandates — delivering target valuation, quality of earnings analysis, financial modelling, regulatory compliance advisory (FEMA, SEBI, Companies Act), and post-deal integration support. This guide maps the complete buy-side M&A process as it operates in practice in India.
Key Takeaways:
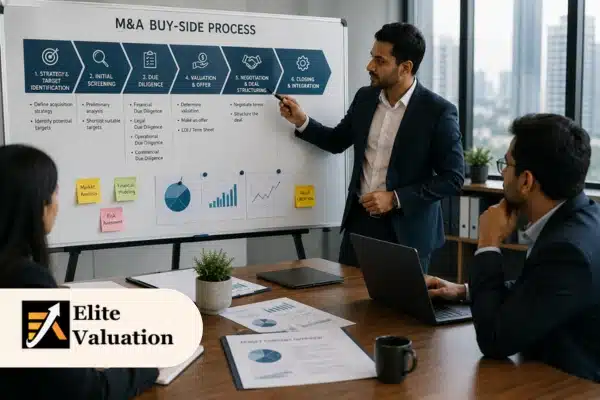
- The M&A buy-side process follows a structured sequence: Strategic Decision → Target Search → Initial Contact → NDA → First Data Analysis → Non-Binding Offer → Due Diligence → Target Valuation → Deal Structuring → Deal Financing → Closing → Post-Merger Integration
- Comprehensive due diligence covers six parallel workstreams: financial & tax, legal, commercial & technical, operational, ESG, and cultural & people
- Quality of earnings analysis is the most consequential due diligence output — it directly determines the valuation multiple applied to EBITDA
- Target valuation uses DCF, comparable company multiples, precedent transactions, and NAV — with synergy adjustments and integration cost overlays
- Deal structure in India (share purchase vs. slump sale vs. scheme) has material tax and liability consequences
- Indian M&A may require CCI, SEBI, RBI/FEMA, NCLT, and sector-specific regulatory approvals
- Post-merger integration — not the deal itself — is where most acquisition value is either captured or destroyed
Phase 1: Strategic Decision and Target Identification
Pre-Deal Phase
Every successful acquisition starts not with a target company but with a clearly articulated strategic rationale. The acquirer must define why it is acquiring, what it expects to gain, and how the acquisition fits into its broader corporate strategy — before any target enters the conversation.
1. Strategic Decision — Define the Acquisition Mandate
The board and leadership define the strategic objective: market expansion, vertical integration, technology acquisition, talent acquisition, geographic entry, or sector consolidation. This stage produces acquisition criteria — target industry, size range (revenue, EBITDA), geographic presence, product/service fit, acceptable valuation multiples, and deal structure preferences. The mandate must also specify capital allocation limits, acceptable leverage, and timeline.
2. Preliminary Target Search — Building the Long List
The M&A advisory team maps the acquisition landscape against defined criteria. This involves industry mapping, competitive analysis, ownership structure screening (promoter-led vs. PE-backed vs. publicly held), financial benchmarking from public data (MCA filings, annual reports, credit ratings), and proprietary deal flow. The output is a long list of 15–30 potential targets, narrowed to 5–8 based on strategic fit, indicative size, and likely seller appetite. In India, proprietary deal flow — targets not publicly marketed — represents the majority of mid-market opportunities.
3. Initial Contact — Approaching the Target
The acquirer or its advisor initiates contact with the target's promoter, board, or sell-side advisor. Founder-owned businesses require relationship-driven engagement; PE-backed exits follow structured process timelines; listed targets involve public disclosure obligations. Initial contact is exploratory — no material confidential information is exchanged.
4. Evaluation of Public Data — Desktop Screening
Before any confidential exchange, the acquirer analyses publicly available information: MCA filings, ROC charge registers, credit reports, industry reports, media coverage, litigation records (NCLT, High Court databases), and patent/trademark registries. For listed targets, SEBI filings, shareholding patterns, and quarterly results provide additional data. This screening identifies red flags before incurring due diligence costs.
Phase 2: NDA, First Data Set Analysis, and Non-Binding Offer
Preliminary Engagement Phase
5. Non-Disclosure Agreement (NDA) — Establishing Legal Protections
A mutual NDA controls the flow of sensitive financial, operational, and commercial data. Indian M&A NDAs typically include: definition of confidential information, permitted use restrictions, non-solicitation of employees and customers, return/destruction of information obligations, and a standstill clause for listed targets.
6. First Data Set Analysis — Preliminary Financial Review
The target provides 3 years of audited financials, management accounts, a business overview, customer/revenue breakdown, and organisational structure. The acquirer performs preliminary analysis: revenue trends, EBITDA margins, working capital patterns, capex intensity, debt structure, and related-party transactions. This stage establishes the indicative valuation range and flags areas for deeper due diligence investigation.
7. Letter of Intent (LOI) / Non-Binding Offer (NBO)
The acquirer submits a Letter of Intent covering: indicative valuation range or enterprise value, proposed deal structure (share purchase, slump sale, or scheme), exclusivity period (typically 60–90 days), due diligence scope and access requirements, key conditions precedent, and indicative timeline. The LOI is generally non-binding on price but exclusivity and confidentiality clauses are binding.
⚠️ Critical: Exclusivity Period The exclusivity clause prevents the target from engaging with other potential acquirers during due diligence. For proprietary deals, exclusivity should always be negotiated before incurring significant due diligence costs.
Phase 3: Comprehensive Due Diligence — The Six Workstreams
Due Diligence Phase
Due diligence is the most critical phase of the buy-side M&A process. It verifies everything the target has represented, identifies hidden risks, quantifies valuation adjustments, and builds the foundation for the definitive purchase agreement.
📌 What Due Diligence Actually Determines
Due diligence directly determines: (a) whether to proceed, (b) the adjusted valuation and final price, (c) the deal structure, (d) the representations, warranties, and indemnities in the purchase agreement, and (e) the post-merger integration plan. A due diligence finding that reduces normalised EBITDA by ₹1 crore — in a deal at 8× EBITDA — reduces the acquisition price by ₹8 crore.
1. Financial & Tax Due Diligence
Quality of Earnings, Working Capital & Tax Risk Analysis
Specialist ESOP consulting
Drives Valuation Directly
- Quality of Earnings (QoE): Normalise EBITDA by removing one-time items, owner perquisites, related-party transactions at non-arm's length prices, aggressive revenue recognition, and unsustainable cost deferrals
- Net Working Capital (NWC): Establish the target NWC level — the "peg" around which closing price is adjusted
- Debt and Debt-Like Items: Identify all obligations treated as debt for the enterprise-to-equity bridge
- Tax Due Diligence: Compliance history, pending assessments, transfer pricing, GST credits, MAT credit utilisation, tax contingency quantification
- Target Modelling: Build a standalone financial model reflecting normalised earnings — foundation for DCF valuation
2. Legal Due Diligence
Corporate Structure, Litigation, Contracts & Regulatory Compliance
Legal Counsel-Led
Directly Impacts Deal Structure
- Corporate governance — shareholder agreements, restrictive covenants, anti-dilution rights, drag-along/tag-along provisions
- Pending and threatened litigation — quantify exposure and probability of material adverse outcomes
- Material contracts — change-of-control triggers in customer, supplier, lease, and licence agreements
- Regulatory compliance — industry-specific licences, environmental clearances, labour law, data privacy (DPDP Act 2023)
- Intellectual property — patent ownership, trademark registrations, employee IP assignment agreements
- Draft & align legal aspects: Identify issues requiring resolution before signing — consent requirements, lender NOCs, regulatory pre-approvals
3. Commercial & Technical Due Diligence
Market Position, Customer Concentration & Technology Assessment
Validates the Investment Thesis
- Market sizing, competitive positioning, and competitive moat analysis
- Customer concentration risk — revenue dependence on top 5/10 customers, churn rates, contract renewal patterns
- Revenue quality — recurring vs. one-time, subscription vs. project-based, pipeline visibility
- Technical assessment: Technology stack, product roadmap, scalability, technical debt, cybersecurity posture
4. Operational & ESG Due Diligence
Supply Chain, Capacity, ESG Compliance & Operational Risks
Post-Deal Integration Input
ESG Increasingly Mandatory
- Supply chain resilience — supplier concentration, single-source dependencies, procurement cost trends
- Manufacturing capacity — utilisation rates, capex requirements, deferred maintenance
- IT systems — ERP maturity, system integration complexity, data migration readiness
- Operational risks: Key-person dependencies, process documentation gaps, scalability constraints
- ESG: Environmental liabilities (pollution control, waste management), governance risks (related-party transactions, board independence), social factors (labour practices)
5. Cultural & People Due Diligence
Management Capability, Retention Risk & Cultural Fit
Most Underestimated Workstream
- People evaluation: Assess management depth below the promoter/CEO — is the business overly dependent on 1–2 individuals?
- Retention risk — identify key employees whose departure would materially impact post-deal performance; design retention mechanisms
- Cultural alignment — working culture, decision-making style, organisational values against the acquirer's culture
- HR compliance — employee contracts, PF and gratuity compliance, pending labour disputes, ESOP obligations
📋 Definitive Purchase Agreement — Key Components
- Normalised EBITDA and quality of earnings report with all adjustments quantified
- Target NWC peg and closing adjustment mechanism
- Complete debt and debt-like items for enterprise-to-equity bridge
- Tax contingency quantification with probability-weighted exposure
- Material litigation summary with financial exposure assessment
- Change-of-control triggers across all material contracts
- Key-person and retention risk assessment with proposed mechanisms
- Integration complexity assessment feeding into the PMI plan
Need Buy-Side Due Diligence or Target Valuation?
Our team delivers financial due diligence, quality of earnings analysis, target valuation (DCF, comparable multiples, NAV), and regulatory compliance advisory (FEMA, SEBI, Companies Act) for mid-market M&A transactions across India.
Phase 4: Target Valuation — How Acquirers Determine What a Business Is Worth
Valuation Phase
Target valuation is where all due diligence findings converge into a single number: the maximum price the acquirer should pay. Unlike regulatory valuation, buy-side M&A valuation answers a commercial question — at what price does this acquisition create value for the acquirer?
| Valuation Method | When Used | Key Considerations |
|---|---|---|
| Discounted Cash Flow (DCF) | Primary — all targets with projectable cash flows | Based on normalised post-due-diligence projections. WACC reflects India risk premium. Sensitivity analysis mandatory |
| Comparable Company Analysis | Cross-check — benchmarking against listed peers | EV/EBITDA and P/E from Indian listed peers. Adjustments for size, liquidity, growth differential, and DLOM for unlisted targets |
| Precedent Transaction Analysis | Cross-check — recent M&A deals in sector | Transaction multiples adjusted for control premium, timing, and market conditions. Indian mid-market data can be limited |
| Asset-Based Valuation (NAV) | Asset-heavy — real estate, manufacturing, holding companies | Fair market value of assets minus liabilities. Useful where earnings are volatile but asset base is substantial |
📌 The Acquirer's Valuation Framework
Standalone Value (normalised earnings) + Synergy Value (cost savings, revenue uplift) — Integration Costs (one-time costs of combining) = Maximum Acquisition Price that delivers the acquirer's required return. The negotiation happens between the seller's expectations and the buyer's maximum — the deal closes when these overlap.
Phase 5: Deal Structuring and Financing in Indian M&A
Structuring & Financing Phase
Common M&A Deal Structures in India
| Structure | Mechanism | Tax & Liability Impact | When Used |
|---|---|---|---|
| Share Purchase | Acquirer buys equity shares from existing shareholders | All liabilities transfer. Seller pays capital gains. Stamp duty varies by state | Most common — clean ownership transfer |
| Slump Sale | Target transfers entire business undertaking as going concern | Selective liability transfer. Seller taxed on slump sale gains. GST exempt if qualifying | Carve-outs; avoiding legacy liabilities |
| Merger / Amalgamation | Target merges into acquirer via NCLT-sanctioned scheme (Sections 230-232) | Tax-neutral if Section 2(1B) conditions met. Requires NCLT, SEBI (if listed), creditor approval | Listed acquisitions, group restructurings |
| Asset Purchase | Acquirer purchases specific assets (not entity) | No automatic liability transfer. GST applicable. Individual contract novation required | When only specific assets needed |
How M&A Deals Are Financed
Deal Financing — Cash, Debt, Equity, or Blended
Structure Impacts Returns
- Cash: Fastest and cleanest. Preserves equity ownership. Reduces liquidity
- Debt (Acquisition Finance / LBO): Leverages target's cash flows. Amplifies equity returns but increases risk. Common for PE
- Equity (Share Swap): Preserves cash but dilutes shareholders. Common in merger schemes
- Blended: Most mid-market deals use a combination — equity, senior debt, and sometimes mezzanine or vendor financing
- Earn-Outs: Contingent consideration based on post-closing milestones. Bridges valuation gaps and aligns seller incentives
What Regulatory Approvals Are Required for M&A in India?
Regulatory Phase
| Regulator | When Required | Typical Timeline |
|---|---|---|
| CCI | Combination thresholds exceeded | 30 days (Green Channel); 150–210 days (Phase I/II) |
| SEBI | Listed target — open offer / preferential allotment | 60–90 days for open offer |
| RBI / FEMA | Cross-border M&A — FDI/ODI | FC-GPR within 30 days; AD bank 2–4 weeks |
| NCLT | Mergers/schemes under Sections 230-232 | 6–12 months |
| Sector Regulators | IRDAI, RBI (NBFC), TRAI, DPIIT | 30 days to 6+ months |
⚠️ Regulatory approval timelines are the most common cause of deal delays. CCI, NCLT, SEBI timelines should be mapped at the LOI stage — not discovered during execution.
Deal Closing: From Definitive Agreement to Ownership Transfer
Closing Phase
📋 Definitive Purchase Agreement — Key Components
- Purchase Price: Fixed price, locked-box, or closing accounts mechanism with NWC adjustment
- Representations & Warranties: Seller's statements — accuracy of financials, no undisclosed liabilities, compliance, valid title
- Indemnities: Seller's obligation to compensate for breaches — caps, time limits, carve-outs
- Conditions Precedent: CCI, SEBI, FEMA approvals; third-party consents; minimum NWC; no MAC
- Non-Compete & Non-Solicitation: Restrictions on seller competing or soliciting customers/employees
- Escrow / Holdback: Portion of consideration held for post-closing indemnity claims
Phase 6: Post-Merger Integration — Where Acquisition Value Is Won or Lost
Integration Phase
Poor post-merger integration is the single largest cause of M&A failure. The deal is only the transfer of ownership — value creation happens in the months and years after. Integration planning should begin during due diligence, not after closing.
Integration Aspects — Day 1 Readiness and First 100 Days
Highest Risk Period
- Day 1 readiness: Ensure payroll, banking, IT access, customer communication, regulatory filings all operational
- Integration Management Office (IMO): Dedicated team with authority, reporting cadence, milestone tracking
- Communication plan: Internal (both entities' employees) and external (customers, vendors, regulators)
Owners Transition & Management Continuity
Critical for Founder-Led Businesses
- In promoter-led Indian businesses, the founder's relationships are often the most valuable intangible asset
- Transition agreements: Define departing promoter's role, duration, handover responsibilities, incentive alignment
- Knowledge transfer: Formalise tacit knowledge — customer history, vendor patterns, regulatory navigation
Operational Optimisation & Systems Integration
Where Synergies Are Captured
- Process harmonisation: Align procurement, manufacturing, quality control, supply chain
- IT and ERP integration: Often 6–18 months — the most complex workstream
- Vendor rationalisation and cross-selling through combined distribution channels
Cultural Alignment — The Most Underestimated Challenge
Primary Cause of Talent Attrition Post-Deal
- Decision-making style: Flat founder-led hierarchy vs. multi-layer corporate approvals
- Communication cadence: Frequency, transparency, format must be consciously designed
- HR harmonisation: Compensation benchmarking, designation alignment, benefits parity
Asset Turnover & ROI Tracking — Measuring Acquisition Success
Board-Level Reporting
- Track actual vs. projected synergy realisation — revenue, cost, capex avoidance
- Monitor asset turnover, ROCE, and free cash flow against original investment thesis
- Quarterly board reporting on integration milestones, value creation, and risks
- Post-deal review at 12 and 24 months
Where Most Acquirers Go Wrong — Common Buy-Side M&A Mistakes
❌ Skipping quality of earnings and relying on audited financials at face value
Audited financials confirm GAAP compliance — not that earnings are sustainable. Related-party revenue, aggressive recognition, and below-market owner compensation routinely overstate EBITDA by 15–30% in Indian mid-market targets.
Consequence: Overpaying by the EBITDA multiple applied to inflated earnings.
❌ Ignoring change-of-control clauses in material contracts
Customer contracts, bank facilities, leases often contain change-of-control termination triggers. If top customers exit post-deal, the acquirer has purchased a business without its revenue base.
Consequence: Revenue erosion post-closing; inability to realise the investment thesis.
❌ Choosing deal structure for convenience rather than tax and liability analysis
Share purchase vs. slump sale vs. scheme has material consequences for stamp duty, capital gains, GST, liability transfer, and contract continuity.
Consequence: Avoidable tax leakage; unexpected legacy liability exposure.
❌ Treating post-merger integration as an afterthought
Integration planning must begin during due diligence. Key-person attrition, customer defection, IT disruption, and cultural clashes in the first 100 days destroy more value than overpaying by 10%.
Consequence: Value destruction; key talent departure; synergy capture failure.
❌ Failing to map regulatory approvals at the LOI stage
CCI filings, NCLT proceedings, SEBI open offer timelines add 3–12 months. Discovering them mid-execution derails the transaction.
Consequence: Deal timeline extension; cost escalation; seller fatigue leading to deal collapse.
❌ Underestimating cultural due diligence in founder-led businesses
In Indian mid-market M&A, the founder is often the business. If the founder exits without structured transition, the acquirer inherits an organisation that functions differently from what was modelled.
Consequence: Operational disruption; customer and employee attrition; lower post-deal performance.
Planning an Acquisition? Get the Valuation and Due Diligence Right.
From target identification to post-merger integration — our team delivers the financial analysis, valuation, and regulatory compliance advisory that mid-market acquirers need to close deals with confidence.
Closing Summary: The Buy-Side M&A Process as a Discipline
A successful acquisition is not a single transaction — it is a disciplined process spanning months of strategic planning, target identification, rigorous due diligence, defensible valuation, careful structuring, and years of post-merger value creation. In India's regulatory environment, FEMA, CCI, SEBI, NCLT, and Income Tax implications layer additional complexity onto every stage. At Elite Valuation, we serve as the valuation, due diligence, and regulatory compliance partner on buy-side M&A transactions — ensuring the acquirer's investment thesis is tested, the price is defensible, the structure is optimised, and the integration delivers the value that justified the deal.
Frequently Asked Questions — M&A Buy-Side Process in India
CA Sagar Shah, Founder
Mr Sagar Shah is the Founder of Elite Valuation and leads the firm’s Valuation and Advisory practice. With over 15+ years of professional experience.