ESOP / SAR Advisory
SAR / Phantom Stock vs ESOP: Which Plan Worked Better for a Private Company?
SAR vs ESOP
Phantom Stock
Employee Retention
Ind AS 102
Dilution vs Cash Settlement
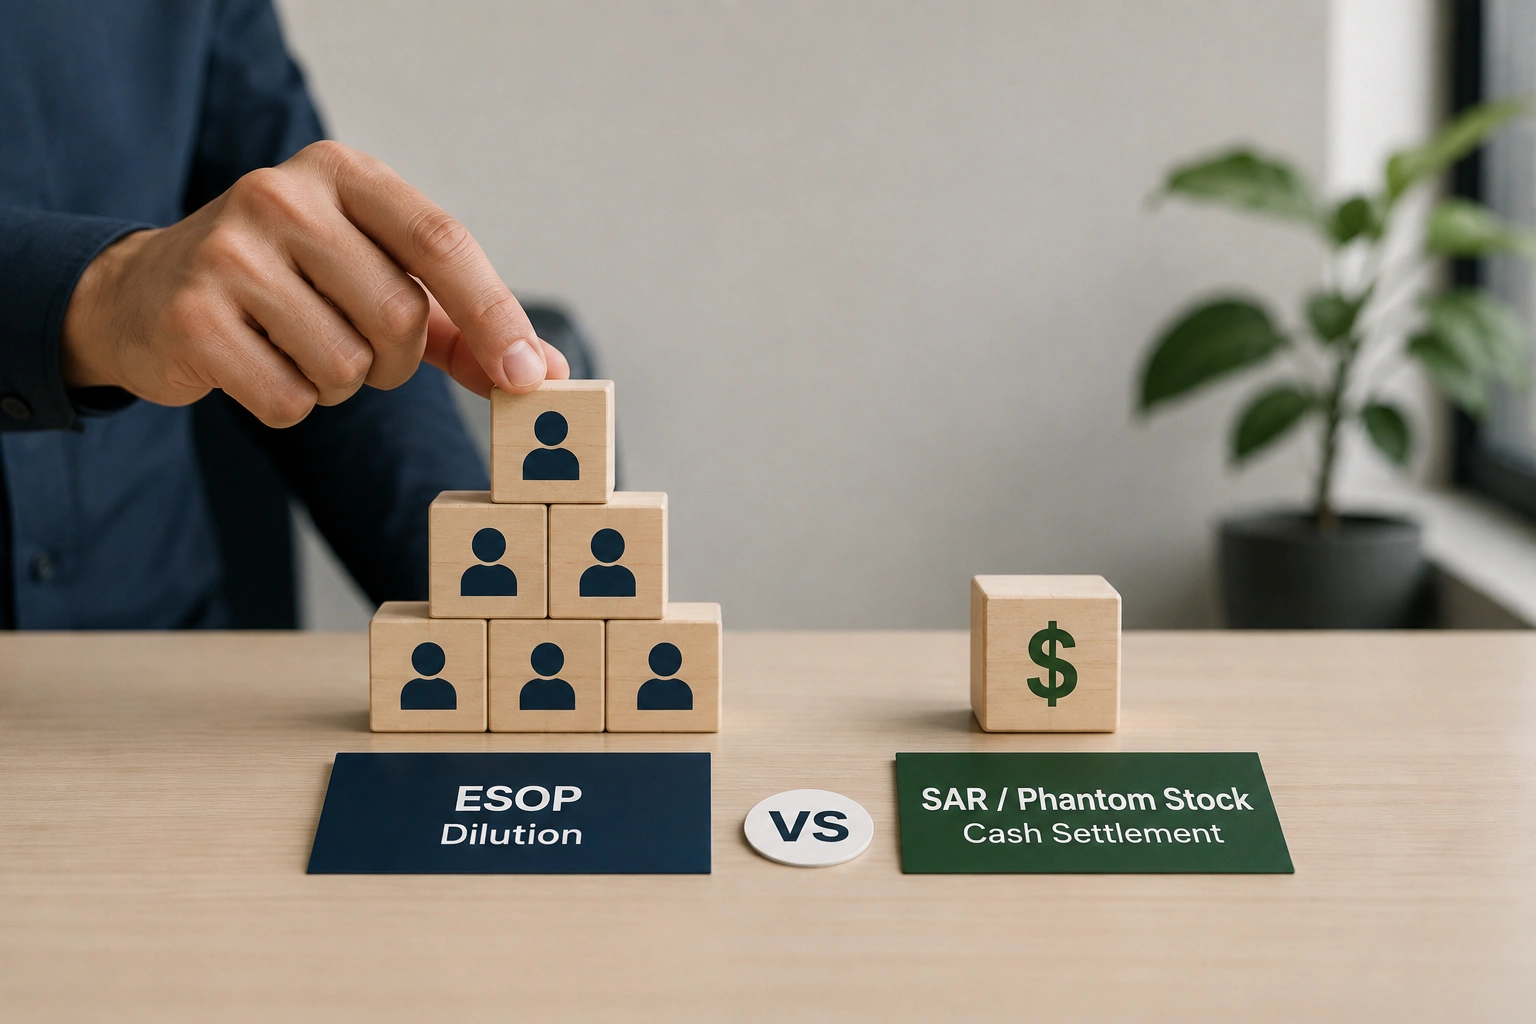
A profitable Indian private company wanted to retain 20 senior employees without immediately issuing equity or creating a large cap-table pool. Elite Valuation modelled the same 50,000-unit incentive as an ESOP and as a cash-settled SAR / phantom-stock plan. At a current share FMV of ₹400 and a ₹250 exercise/base price, both plans produced ₹2.00 crore employee upside if the business reached ₹650 per share at liquidity. The ESOP created 4.76% post-exercise dilution; the SAR created no dilution but a ₹2.00 crore cash obligation. Given the company's expected strategic exit and strong cash generation, the cash-settled SAR was selected.
50,000
4.76%
₹2.00 cr
₹2.00 cr
01. The Company Wanted Retention Economics Without Automatic Dilution
The client was an eight-year-old Indian technology-enabled services company with approximately ₹72.00 crore revenue, ₹11.50 crore EBITDA and strong operating cash generation. The founders expected a strategic liquidity event within three to four years but did not want to add a large permanent ESOP pool immediately before that process.
Management wanted to create long-term upside for 20 senior employees. The proposed award size was economically equivalent to 50,000 units with a base/exercise price of ₹250. Current fair value of the underlying share was approximately ₹400.
Under an ESOP, employees would acquire actual shares on exercise and become shareholders. Under a cash-settled SAR / phantom-stock plan, employees would receive the appreciation in value above ₹250 without becoming shareholders.
Elite Valuation compared the two alternatives on the same business assumptions so the decision could be driven by dilution, cash cost, accounting, tax, liquidity and employee communication rather than by the label attached to the plan.
"ESOP and phantom stock can deliver similar upside, but they move the cost to different places: ESOP moves it into dilution; cash-settled SAR moves it into the company's future cash flow and liability remeasurement."
02. Six Questions That Changed the Instrument Choice
The company did not ask which plan was more popular. It asked which plan best matched its ownership strategy, liquidity profile and employee population.
| Decision Area | Why It Mattered |
|---|---|
| Shareholder Dilution Ownership Impact | Issuing 50,000 ESOP shares against 10,00,000 existing shares would create 10,50,000 post-exercise shares and dilute existing shareholders by approximately 4.76%. A cash-settled SAR creates no equity dilution. |
| Employee Exercise Funding Liquidity Friction | ESOP employees would need to fund ₹1.25 crore of aggregate exercise price before receiving shares. Under the SAR structure, employees would not need to fund an exercise payment to obtain the appreciation value. |
| Company Cash Requirement Settlement Risk | ESOP preserves company cash and actually brings in exercise proceeds. SAR does the opposite: if share value reaches ₹650, the company must fund a ₹2.00 crore cash payout. |
| Accounting Volatility P&L Re-Measurement | Equity-settled ESOP expense is based primarily on grant-date fair value. Cash-settled SAR liability is remeasured at each reporting date until settlement, causing expense to move with the share-price trajectory. |
| Tax and Employee Experience Take-Home Outcome | An ESOP can create a perquisite-tax event on exercise followed by capital-gains taxation on later sale. A pure cash-settled SAR produces cash employment remuneration through payroll rather than an employee-owned capital asset. |
| Exit Strategy Instrument Fit | The company expected a strategic sale and had strong projected cash generation. That made a cash payout at liquidity more manageable than permanent dilution across future funding and exit scenarios. |
03. Modelling Both Plans on the Same ₹650 Liquidity Outcome
The analysis kept employee economics constant and changed only the settlement mechanism so the company could see where each plan created value and cost.

Phase A: Set the common economic terms
Both structures used 50,000 units, current share FMV of ₹400, base/exercise price of ₹250, a four-year service period and an assumed liquidity value of ₹650 per share.
Phase B: Model the equity-settled ESOP
Employees would pay 50,000 × ₹250 = ₹1.25 crore to exercise. They would then own shares worth ₹3.25 crore at ₹650, creating ₹2.00 crore economic gain. Existing shareholders would be diluted by 50,000 ÷ 10,50,000 = 4.76%.
Phase C: Calculate ESOP grant-date accounting value
Using Black-Scholes with S ₹400, K ₹250, four-year expected life, 40.00% volatility, 7.00% risk-free rate and nil dividend yield produced approximately ₹230.67 fair value per option. Total grant-date value was ₹1.1533 crore, recognised over the four-year service period subject to vesting/forfeiture assumptions.
Phase D: Model the cash-settled SAR liability
The SAR used the same ₹250 base price but settled only the appreciation in cash. At ₹650, the company would pay (₹650 − ₹250) × 50,000 = ₹2.00 crore. Employees would receive the same gross economic upside without exercise funding or share ownership.
Phase E: Remeasure the SAR through the vesting period
The cash-settled liability was remeasured as share value changed. Illustratively, the cumulative liability increased from approximately ₹0.34 crore at Year 1 to ₹0.77 crore at Year 2, ₹1.34 crore at Year 3 and finally ₹2.00 crore at settlement.
Phase F: Select the plan that best matched the company's objective
Because the primary objective was retaining senior employees without changing the shareholder cap table, the company selected the cash-settled SAR. Management also ring-fenced future liquidity planning so the expected ₹2.00 crore settlement could be funded from transaction proceeds or company cash at the liquidity event.
6 ESOP vs SAR comparison components applied:
Same employee upside, different company economics:
| Metric | ESOP | Cash-Settled SAR / Phantom Stock |
|---|---|---|
| Equivalent units | 50,000 options | 50,000 SAR units |
| Current share FMV | ₹400 | ₹400 reference value |
| Exercise / base price | ₹250 | ₹250 |
| Liquidity share value | ₹650 | ₹650 |
| Employee exercise funding | ₹1.25 cr | Nil |
| Gross employee upside | ₹2.00 cr | ₹2.00 cr |
| Equity dilution | 4.76% | Nil |
| Company cash at liquidity | Receives ₹1.25 cr exercise proceeds | Pays ₹2.00 cr settlement |
Ind AS 102 accounting comparison:
| Year / Item | ESOP — Equity Settled | SAR — Cash Settled |
|---|---|---|
| Grant-date fair value | ₹230.67/option | Initial fair value used but liability continues to remeasure |
| Total original grant value | ₹1.1533 cr | Not fixed for life of plan |
| Year 1 cumulative liability | Equity reserve — no FV remeasurement | ₹0.34 cr |
| Year 2 cumulative liability | Equity reserve — no FV remeasurement | ₹0.77 cr |
| Year 3 cumulative liability | Equity reserve — no FV remeasurement | ₹1.34 cr |
| Final cumulative cost / liability at settlement | Grant-date based expense, subject to vesting | ₹2.00 cr cash settlement |
Decision matrix for this company:
| Objective | Better Fit | Why |
|---|---|---|
| Preserve cash during growth years | ESOP | No future cash settlement; exercise can bring cash into company |
| Avoid shareholder dilution | SAR / Phantom | No shares issued on settlement |
| Create actual ownership culture | ESOP | Employees can become shareholders after exercise |
| Keep cap table clean before strategic sale | SAR / Phantom | Employees participate economically without adding shareholders |
| Client's dominant objective | SAR / Phantom selected | No dilution + senior retention + expected liquidity event |
Accounting, corporate and tax framework considered
Ind AS 102 — equity-settled ESOP: employee services are generally measured using grant-date fair value of the equity instruments, with expense recognised over the vesting period subject to the applicable vesting-condition requirements.
Ind AS 102 — cash-settled SAR: a cash-settled share-based payment creates a liability measured at fair value and remeasured at each reporting date and at settlement. The cumulative cost ultimately reflects the cash amount paid for vested awards.
Companies Act ESOP framework: an actual employee stock option that gives employees a right to subscribe to company shares requires the applicable Section 62(1)(b) and Rule 12 approvals and records for an unlisted company.
Pure cash-settled phantom/SAR plan: no company shares are issued merely because the cash payout references share value. The plan should nevertheless be documented through appropriate Board/employment approvals and reviewed against the company's Articles, shareholder agreements and accounting framework.
Tax distinction: ESOP taxation generally has an exercise-stage perquisite component followed by capital-gains consequences on later sale of the shares. A pure cash-settled SAR does not itself create an employee-owned share and the cash payout is processed as employment remuneration under the applicable payroll/TDS framework.
04. Result: SAR Won on Dilution; ESOP Would Have Won on Cash Conservation
The selected instrument matched the company's actual constraint rather than being chosen from a generic ESOP-versus-phantom-stock checklist.
50,000
4.76%
₹2.00 cr
₹2.00 cr
liability
- The ESOP alternative would have created 4.76% dilution after exercise, while the selected SAR preserved the founders' and existing investors' percentage ownership.
- Both plans delivered the same ₹2.00 crore gross appreciation value at a ₹650 liquidity value because both used the same 50,000 units and ₹250 base/exercise price.
- Employees avoided the ₹1.25 crore aggregate exercise-funding requirement that would have existed under the ESOP structure.
- The company accepted the trade-off: its SAR liability grew with share value and ultimately required a ₹2.00 crore cash settlement rather than a fixed grant-date equity expense.
- The final design fit the company's strategic-sale objective: senior employees participated in value creation without becoming new shareholders immediately before the expected liquidity event.
05. Five Lessons from SAR vs ESOP Plan Design
The right instrument is determined by the company's constraints, not by whether one structure appears simpler on day one.
Compare the plans on identical economics
Using the same 50,000 units, ₹250 base price and ₹650 liquidity value made the real differences visible: dilution, funding, accounting and ownership—not employee upside.
SAR removes dilution but does not remove cost
The ₹2.00 crore employee value still had to come from somewhere. Under SAR it became a company cash liability instead of dilution borne by shareholders.
ESOP can be better for cash-constrained startups
An early-stage company with limited liquidity may prefer an equity-settled ESOP because it preserves cash and can even receive exercise proceeds when employees exercise.
Cash-settled plans create accounting volatility
The SAR liability increased from approximately ₹0.34 crore to ₹2.00 crore as the share value rose. That P&L volatility should be understood before the plan is approved.
Employees must understand that phantom units are not shares
A SAR can replicate economic participation without voting, dividend or shareholder rights. Clear communication prevents employees from assuming they own actual equity before settlement.
Why Choose Elite Valuation
Elite Valuation helps private companies compare ESOPs, SARs, phantom stock and other long-term incentive structures before the plan is drafted or communicated to employees.
The firm's approach integrates cap-table dilution, employee economics, Black-Scholes or other valuation techniques, Ind AS 102 accounting, cash-settlement modelling, corporate approvals and employee-tax implications rather than treating plan design as a legal-document exercise alone.
As an IBBI Registered Valuer with CA and CS capability, Elite Valuation can support the full lifecycle from instrument selection and scheme design through valuation, accounting and ongoing employee-equity administration.
IBBI Registered Valuer
CA & CS Led Advisory
ESOP / SAR Advisory
Ind AS 102
ESOP Scheme Design
SAR / Phantom Stock
ESOP Valuation
Share-Based Payment Accounting
Cap Table & Dilution
Sagar Shah — CA | CS | IBBI Registered Valuer | Founder, Elite Valuation
Sagar Shah is the founder of Elite Valuation and a qualified Chartered Accountant, Company Secretary, and IBBI Registered Valuer with prior experience at Ernst & Young. He specialises in business Valuation, M&A advisory, ESOP Valuation, FEMA compliance, and regulatory Valuation across the Companies Act, SEBI, and RBI frameworks. Elite Valuation operates pan-India from Ahmedabad, advising companies of all stages and sizes.