ESOP Advisory Case Study
End-to-End ESOP Scheme Design & Structuring for a Bootstrapped D2C Brand
ESOP Policy Design
Cliff Period Strategy
Vesting Mechanics
Companies Act Compliance
Bootstrapped Startup
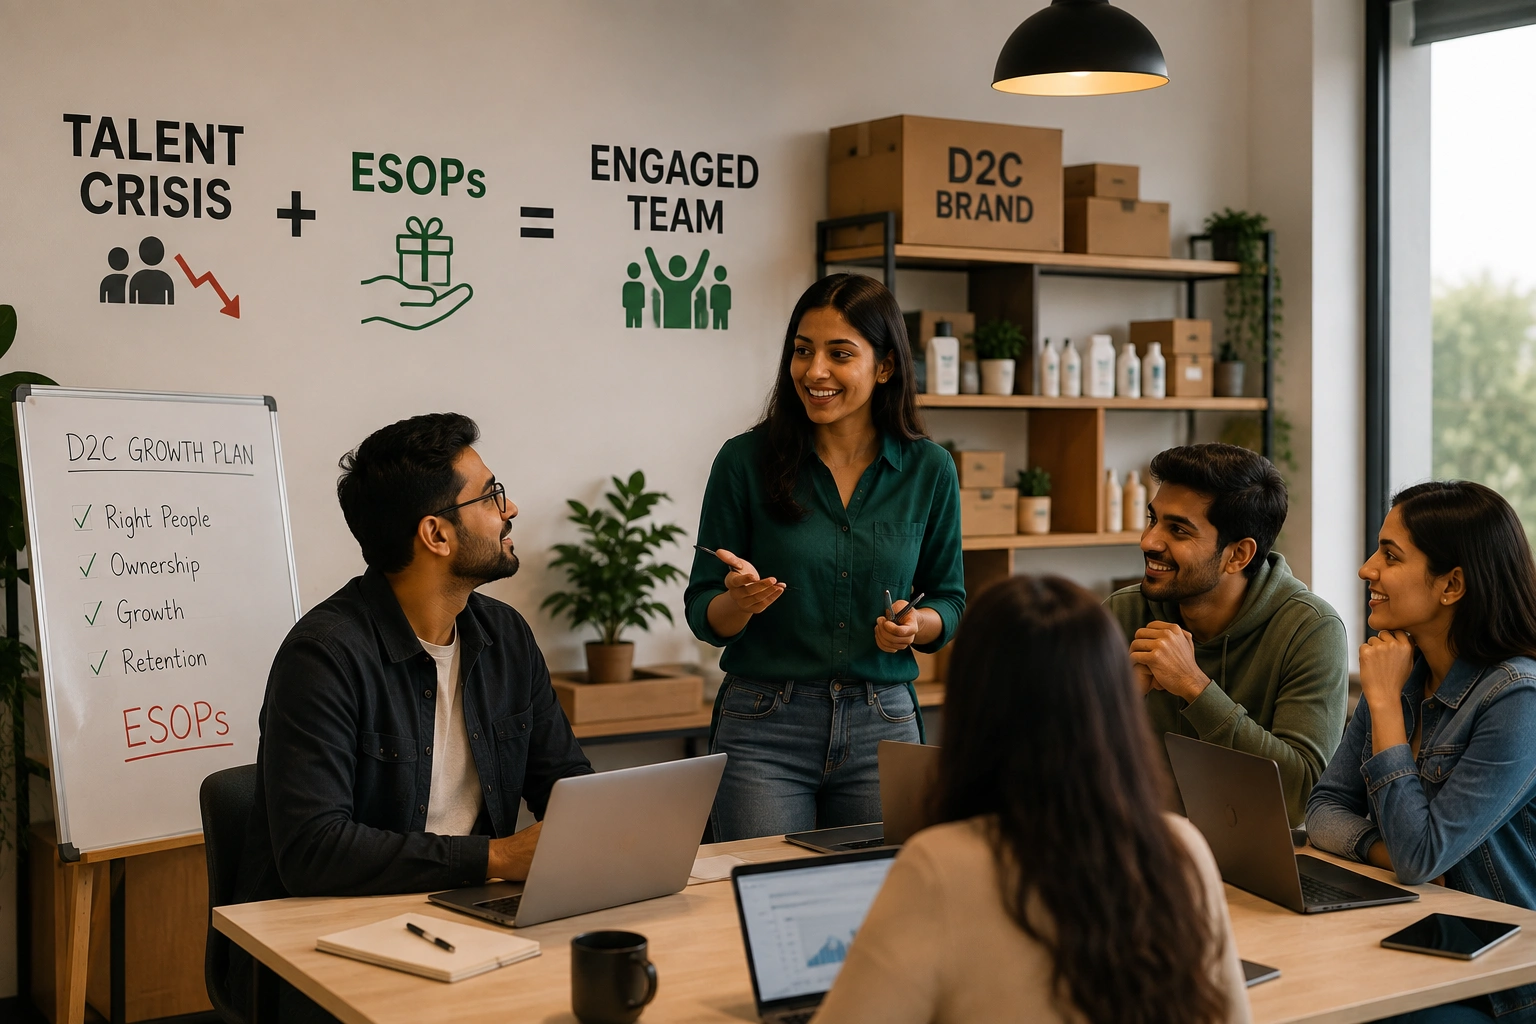
A bootstrapped Direct-to-Consumer (D2C) brand was scaling rapidly but lacked the cash reserves to pay market-rate salaries to its top talent. To retain critical marketing and tech leads, the founders needed to offer equity. However, simply handing out shares risks permanent cap-table damage if employees leave early. Elite Valuation designed an end-to-end Employee Stock Ownership Plan (ESOP) scheme from scratch. We sized a 10% pool, established a 1-year cliff and 4-year graded vesting schedule, drafted robust "Bad Leaver" clawback clauses, and managed the entire Companies Act compliance process, ensuring the founders retained voting control while providing massive potential upside to their team.
10.0%
50
4 Yrs
Sec 62(1)(b)
01. Business Context & Retention Challenge
The client was a profitable, bootstrapped D2C consumer goods brand. As they prepared to expand their omnichannel presence, they faced a talent crisis. Heavily funded competitors were actively poaching their Head of Performance Marketing and Lead Supply Chain Manager with massive cash offers.
The founders recognized they could not win a cash war. Their only competitive advantage was offering wealth creation through equity. However, the founders were hesitant; they had heard horror stories of startups giving away equity, only for the employee to quit six months later and sit passively on the cap table.
The company needed a structured Employee Stock Ownership Plan (ESOP). An ESOP is not a share handout; it is a right granted to an employee to purchase shares at a predetermined price, *after* they have proven their loyalty over a defined period (vesting).
Elite Valuation was engaged to handle the end-to-end ESOP lifecycle: from mathematical pool sizing and policy drafting to board approvals and employee communication.
"An ESOP is a corporate contract, not just a compensation perk. A poorly drafted ESOP policy can result in dead equity, hostile ex-employees on your cap table, and severe pushback from future VC investors."
02. What Made the ESOP Design Difficult
Designing an ESOP policy requires balancing aggressive employee motivation with rigorous legal protection for the founders.
| Challenge Area | Description & Structural Impact |
|---|---|
|
Pool Sizing Dilution Management | Creating an ESOP pool dilutes the founders. If the pool is too small (e.g., 2%), it won't attract talent. If it is too large (e.g., 20%), the founders give away too much control unnecessarily. |
|
Vesting vs. Cliff Mechanics Retention Strategy | If options vest immediately, there is no retention incentive. We had to legally structure a timeline that forced employees to stay to earn their equity, without demoralizing them. |
|
Leaver Scenarios Cap Table Protection | What happens to vested options if an employee is fired for fraud (Bad Leaver) versus leaving due to illness (Good Leaver)? The policy had to dictate exact clawback mechanisms. |
|
Liquidity Event Definition Exit Clarity | Employees want to know how they turn options into cash. The policy had to define what constitutes an "exit" (IPO, strategic buyout, or secondary sale) without legally forcing the company to buy back shares. |
03. Methodological Execution of the ESOP Scheme
Elite Valuation approached the ESOP creation systematically, moving from cap table mathematics to legal drafting and statutory compliance.

Phase A: Cap Table Modeling & Pool Sizing
We analyzed the company's hiring roadmap for the next 3 years. Based on industry benchmarks for key leadership roles (e.g., CTO expects 1-2%, VP expects 0.5%), we modeled the dilution impact. The founders approved carving out exactly 10.0% of the fully diluted equity to form the ESOP pool, striking the perfect balance between retention power and founder control.
Phase B: ESOP Policy Drafting (Vesting & Cliffs)
We drafted the master ESOP Scheme document. To protect against early attrition, we instituted a mandatory 1-year Cliff (if an employee leaves before 12 months, they get zero options). Post-cliff, the options followed a 4-year graded vesting schedule (10% Year 1, 20% Year 2, 30% Year 3, 40% Year 4), heavily backloading the rewards to incentivize long-term loyalty.
Phase C: Exercise Price & Leaver Clauses
We set the Exercise Price (the price the employee pays to convert the option to a share) at the face value of the share (₹10), ensuring maximum upside. Crucially, we drafted strict "Bad Leaver" clauses: if an employee is terminated for cause or joins a direct competitor, all options (even vested ones) are immediately canceled and returned to the pool.
Phase D: Statutory Compliance & Rollout
An ESOP scheme must be legally approved under Section 62(1)(b) of the Companies Act, 2013. We drafted the Board Resolutions, the Explanatory Statement for the Shareholders' EGM, and filed the necessary MGT-14 forms with the ROC. Finally, we prepared individualized Grant Letters for the 50 employees.
6 Key Components of the ESOP Architecture:
The importance of Employee Sensitization
A common failure point in ESOP implementation is communication. If you hand an employee a complex legal document, they won't value it. Elite Valuation conducted a town-hall session with the 50 granted employees. We explained the difference between an Option and a Share, how the cliff works, the tax implications upon exercise (perquisite tax), and provided a customized Excel calculator showing their potential wealth creation if the company reached a ₹500 Crore Valuation. This turned the legal document into a tangible retention tool.
04. Scheme Conclusion & Corporate Impact
The structured ESOP rollout solved the immediate talent crisis without draining the company's vital cash reserves, while keeping the cap table pristine.
10.0%
Zero
30 Days
Sec 62
- The company successfully retained its Head of Performance Marketing and Supply Chain Lead, who rejected higher cash offers in favor of the ESOP upside.
- The founders' control was protected. The 1-year cliff and strict Leaver clauses guaranteed that only those who built long-term value would share in the equity.
- The company avoided massive immediate legal and tax complications by clearly defining the ESOP as an "Option to buy" rather than an outright share grant.
- The cap table was structured flawlessly, ensuring that when the company eventually seeks Series A venture capital, the investors will not demand a restructuring of the employee equity pool.
05. Lessons from ESOP Design & Structuring
Creating an ESOP is an exercise in human psychology backed by rigid corporate law.
Cliffs save cap tables
Never grant immediate vesting. If a senior hire is a bad cultural fit and leaves in month six, an ESOP without a cliff means they walk away with permanent equity. A 1-year cliff is an absolute necessity.
Define "Liquidity" clearly
Employees must understand that unlisted shares are illiquid. The policy must explicitly state that options only turn into cash during a defined liquidity event (like an acquisition or an organized secondary sale), managing expectations upfront.
Taxation dictates timing
In India, employees pay perquisite tax when they exercise an option (convert it to a share). If they exercise too early without a liquidity event, they pay out-of-pocket tax on illiquid shares. Designing the exercise window to align with liquidity events is crucial.
Compliance is not optional
Issuing an informal "promise of equity" letter is illegal and unenforceable. ESOPs must be routed through the Board, approved by Shareholders via Special Resolution, and filed with the ROC to be valid.
Why Choose Elite Valuation for ESOP Advisory
Elite Valuation supports founders, HR leaders, and corporate boards with end-to-end ESOP Scheme Design, Structuring, and ongoing ESOP Valuation (Rule 11UA) compliance.
We go beyond Valuation. We architect the entire equity incentive framework. Our team models dilution impacts, drafts customized vesting and cliff mechanics, establishes robust Good/Bad Leaver clauses, and manages the entire Companies Act compliance lifecycle to ensure your cap table remains investor-ready.
Led by Sagar Shah (CA, CS, IBBI Registered Valuer), Elite Valuation provides the strategic legal and financial depth required to align your employees' wealth creation with your company's growth.
IBBI Registered Valuer
CA & CS Led Advisory
Cap Table Strategy
Pan-India Operations
ESOP Scheme Design
Policy Drafting
Companies Act Compliance
Rule 11UA Valuation
Employee Sensitization
Sagar Shah — CA | CS | IBBI Registered Valuer | Founder, Elite Valuation
Sagar Shah is the founder of Elite Valuation and a qualified Chartered Accountant, Company Secretary, and IBBI Registered Valuer with prior experience at Ernst & Young. He specialises in business Valuation, M&A advisory, ESOP Valuation, FEMA compliance, and regulatory Valuation across the Companies Act, SEBI, and RBI frameworks. Elite Valuation operates pan-India from Ahmedabad, advising companies of all stages and sizes.