A pitch deck for Series A, B and C funding in India needs a clear investment story supported by valuation, financial forecasts and a reconciled cap table. The investor is not asking whether the business is interesting. The investor is asking what the company is worth before the new money, how much of the company the new money buys, what the company does with the cash, and what return the investor makes at the exit. Companies preparing a round, an IPO or a sale search for help with exactly these questions, and this guide sets out what the deck must prove at each stage, the numbers investors test first, the dilution and preference maths, the Indian rules on share issuance, and how the pitch changes for an IPO or an exit.
Key takeaways
- The Valuation slide carries the round. It must state the pre-money value, the amount raised, the post-money value, the new investor’s stake and the basis for the price, in a form the investor can recompute in one minute.
- A last-round price is not a Valuation. Investors discount a prior price that was set on different metrics, a different structure or a different market, and they will ask for the basis behind it.
- Dilution is planned across two or three rounds, not one. An ESOP pool top-up that is placed in the pre-money figure reduces the effective price that existing shareholders receive.
- Preference terms change what each investor gets at a sale. At a lower exit, a 1x preference can take more than the investor’s percentage of the equity, so the deck must show the waterfall, not only the stake.
- Check each issue against its applicable company-law, tax and FEMA requirements. Do not assume a commercial fundraising value is the prescribed tax value or that every subscription needs the same reports.
- An IPO deck and a private round deck must tell one story. A pre-IPO placement price that sits far from the issue price invites questions from the regulator, the underwriters and the analysts.
Who This Guide Is For
Founders often treat the pitch deck as a design task, and investors treat it as a set of numbers. The gap between the two is where most growth-stage rounds slow down. A deck with a strong product story and a Valuation slide that does not reconcile may face a lower offer, a longer diligence period or a request to reconcile the financials before the cheque is written.
This guide is written for companies that are raising a Series A, Series B or Series C round, preparing an IPO, or preparing a sale of the company or a stake. It does not address early seed rounds, which follow different logic. For the Valuation method that sits behind a growth-stage price, see our company Valuation in India guide. For the share side of an issue, see share Valuation in India, and for the buyer side of a sale, see M&A buy-side process in India.
For hands-on preparation and review, explore our pitch deck services in India. This guide focuses on the valuation, dilution and investor metrics behind growth-stage decks.
What Must a Pitch Deck for Series A, B, C, an IPO or an Exit Prove in India?
Each stage asks a different question, so the deck changes with the stage. An early Series A investor wants evidence that a repeatable motion exists. A Series B investor wants proof that the motion scales without the margin collapsing. A Series C investor, or a pre-IPO investor, wants the numbers to stand up to a diligence team, an auditor and eventually a public market. Table 1 sets out what each stage tests and the Valuation basis that usually applies.
Evidence to Show at Each Funding Stage
| Stage | The question the investor asks | Valuation basis usually used | What the deck must show |
|---|---|---|---|
| Series A | Is there a repeatable way to acquire and keep customers? | Revenue multiples, comparable rounds and a scenario-based forecast | Early revenue quality, retention cohorts, unit economics, and a use of funds tied to milestones |
| Series B | Does growth hold as the company scales, and does the margin improve? | Revenue or gross profit multiples cross-checked with a discounted cash flow | Reconciled revenue, contribution margin by segment, burn and runway, and the cap table after the round |
| Series C | Can later-stage growth, governance and a credible liquidity path withstand diligence? | Discounted cash flow, earnings multiples and comparable listed companies | Audited numbers, a board-ready forecast, governance, and a clear route to liquidity |
| IPO | Can the price be justified to public investors, the regulator and the underwriters? | Pre-issue Valuation consistent with the issue price and listed peers | A story that matches the offer document, restated financials where needed, and pre-IPO placements priced on the same basis |
Evidence to Show at Each Funding Stage: Exit (sale)
| Stage | The question the investor asks | Valuation basis usually used | What the deck must show |
|---|---|---|---|
| Exit (sale) | What will a buyer pay for the cash flows it will own? | Buyer’s discounted cash flow, synergies and precedent transactions | Normalised earnings, clean customer contracts, and a buyer-ready data room |
Must know: the stage sets the number, the deck sets the story
The same company can carry three different Valuations in one year, depending on whether it is raising, listing or selling. A deck that claims a single unsupported value for all three will be challenged. Keep one set of assumptions, then show how the value changes with the purpose and the stage.
How Should the Valuation Slide Work in a Series A, B or C Pitch Deck?
The Valuation slide has five numbers, and each one must be consistent with the others: the pre-money Valuation, the amount raised, the post-money Valuation, the new investor’s percentage and the number of new shares issued at the round price. If one of these does not reconcile with the others, the investor will stop the meeting and recompute it. The slide should also state whether the pre-money figure includes an ESOP top-up, because that choice moves the effective price for every existing shareholder.
Investors ask one further question in almost every growth-stage meeting: what is the basis for the price? A defensible answer names the method, the key inputs and the sensitivity. A range is better than one figure, and the range should be built from methods that do not depend on each other. A revenue multiple from listed peers is a cross-check on a discounted cash flow. A prior round is a fact, not a method.
The last round is a fact, not a Valuation
Founders often open with the last round’s price and expect it to carry the new round. Investors treat the last price as the outcome of a negotiation at a different date, on different metrics and sometimes with different preference terms. A deck that rests on the last price must explain what has changed since then, in revenue, margin, retention or market conditions, and it must show the effect of the preference terms on the new price.
How should a Valuation range be built for the pitch?
Present a low, base and high value, and state what drives each case. The three cases should differ on the inputs investors test, such as revenue growth, retention and margin, not on arbitrary multiples. A simple range table in the appendix gives the investor the working. In the deck itself, one line per method is enough: the method, the input range and the resulting value.
Valuation Methods and Supporting Inputs
| Method | Main input investors test | What the deck should state |
|---|---|---|
| Revenue or ARR multiple | Revenue quality: recurring share, retention and growth | The multiple range, the peer set or round set used, and why the company sits in the range |
| Discounted cash flow | Forecast margins, capital needs and the discount rate | The forecast horizon, the discount rate build-up and the terminal assumption |
| Earnings multiple (later stage) | Normalised EBITDA or profit after tax | The normalisation adjustments and the listed or transaction peers |
| Net asset value (cross-check) | Net assets and liabilities at fair value | An asset-based cross-check where appropriate; not a guaranteed floor or the default method for a software or consumer company |
Need the Valuation Slide Checked Before the Investor Meeting?
Elite Valuation reconciles the pre-money, the round size, the post-money and the new investor’s stake, then tests the method and the range the deck relies on. Share the latest management accounts, the cap table and the term sheet, and the firm will identify reconciliation gaps and assumptions that need support before diligence.
Request a Valuation Slide ReviewPitch Deck Valuation | Series A, B and C Rounds | Cap Table Dilution | Pre-IPO Valuation | Exit Valuation
Which Numbers Do Series B and Series C Investors Test First?
Investors test a small set of numbers before they test the story, and the same numbers come back in every term sheet discussion. The table below lists them, what the investor is checking, and the definition trap that causes most disagreements. The definitions must be written into the deck’s appendix, because an unclear definition is treated as a red flag, even when the underlying business is sound.
Investor Metrics and Definition Checks
| Metric | What the investor checks | Definition trap |
|---|---|---|
| Annual recurring revenue (ARR) | Whether the recurring base is real, contracted and reconciled to receipts | One-time implementation fees and pilots counted as recurring |
| Net revenue retention | Whether existing customers expand, hold or leave over twelve months | A cohort definition that changes between periods |
| Gross margin | Whether the product earns a return after hosting, support and delivery cost | Support or delivery cost left out of cost of revenue |
| Burn multiple | How much cash is spent to add each unit of net new recurring revenue | Net burn that includes or excludes financing flows without a stated basis |
| CAC payback | How long it takes gross profit from a new customer to recover the cost of acquiring it | Acquisition cost that leaves out sales salaries and marketing overheads |
| Cash runway | How many months the company funds itself after the round, at the forecast burn | Runway that assumes collections the company has not yet received |
What to put in the appendix before the first meeting
- A one-page definition sheet for every metric in the deck, with the period and the basis used.
- An ARR bridge from opening to closing, split into new, expansion, contraction and churn.
- A reconciliation of management accounts to the audited or reviewed figures, with the differences explained.
- The cash runway table at the forecast burn, showing the month in which the round money runs out.
How Much Dilution Should a Series A, B or C Round Cost the Founders?
Dilution is the reduction in an existing holder’s percentage when new shares are issued. In a primary round it depends on the round size and the pre-money Valuation. The new investor’s stake equals the amount raised divided by the post-money Valuation. The existing holders’ stake falls by the same proportion, before any ESOP top-up. The formula is simple, but the figures are often presented without the post-money, and that makes the round look cheaper than it is.
The illustration below uses hypothetical figures to show how the stake moves across three rounds. The figures are not a forecast for any company or a real transaction. Each round is a primary equity issue with no pool top-up, secondary sale, fees or convertible securities. Percentages use the fully diluted post-money base at that round; an earlier investor is diluted again in later rounds.
Illustrative Primary-Round Dilution
| Round (hypothetical) | Pre-money (₹ crore) | Amount raised (₹ crore) | Post-money (₹ crore) | New investor’s stake |
|---|---|---|---|---|
| Series A | 400 | 80 | 480 | 16.7% |
| Series B | 900 | 150 | 1,050 | 14.3% |
| Series C | 2,000 | 250 | 2,250 | 11.1% |
On a narrow screen, scroll inside the chart to see all labels.
Where should the ESOP top-up sit: before or after the pre-money?
Investors often ask for the ESOP pool to be topped up before the round, so that the new pool is included in the pre-money. The effect is that the existing shareholders bear the dilution of the new pool, not the new investor. The illustration uses ₹400 crore pre-money and ₹80 crore primary investment, with no existing option pool, secondary sale, fees or convertible instruments. The new pool is 5 per cent of fully diluted shares after both steps. In the pre-money case, the investor retains 80/480 = 16.67 per cent and existing holders retain 78.33 per cent. In the post-round case, the investor’s initial 16.67 per cent and the existing holders’ 83.33 per cent are each multiplied by 95 per cent. Percentages are rounded to two decimals.
Comparing Pre-Money and Post-Round Pool Creation
| Item (hypothetical Series A) | Pool included before investment | Pool created after investment |
|---|---|---|
| Pre-money / new investment (₹ crore) | 400 / 80 | 400 / 80 |
| Post-money before a later pool issue (₹ crore) | 480, including the pool | 480, before creating the pool |
| Existing holders after both steps | 78.33% | 79.17% |
| New investor after both steps | 16.67% | 15.83% |
| New pool after both steps | 5.00% | 5.00% |
| Allocation to existing shares within the stated pre-money (₹ crore) | 376; the pool absorbs 24 of the stated 400 | 400 before the subsequent pool dilution |
Show the ESOP effect on the Valuation slide
State the pool size, whether it sits in the pre-money, and the effective pre-money for existing holders. An investor who finds this out in diligence will treat the omission as a change to the price, so disclosing it at the start protects the round.
How Do Preference Terms and the Exit Waterfall Change the Pitch?
A preferred share, usually a compulsorily convertible preference share (CCPS) for an Indian company, carries a right to receive money before ordinary shareholders at an exit. The most common term is a 1x liquidation preference, which returns the amount invested before any other distribution. Whether the preference is participating or non-participating, senior or pari passu, changes the outcome materially. A deck that shows only the ownership percentage can understate a preferred investor’s payout and overstate what ordinary shareholders receive at a lower exit.
The illustration below uses hypothetical figures. A Series B investor holds exactly 1/7 of the equity (14.2857 per cent, displayed as 14.3 per cent) and a 1x non-participating preference of ₹150 crore, senior to the earlier rounds. This is a standalone post-Series-B example before any Series C dilution. Assume no debt, transaction costs, accrued dividends or competing claims that reduce the stated distributable equity proceeds. It compares an exit at ₹600 crore and at ₹1,500 crore equity value.
Preference Payout at Two Equity Exit Values
| Item (hypothetical, Series B investor) | Exit at ₹600 crore | Exit at ₹1,500 crore |
|---|---|---|
| Share of exit on conversion (exactly 1/7; ₹ crore) | 85.7 | 214.3 |
| Preference amount (1x) | 150.0 | 150.0 |
| Investor takes the greater (₹ crore) | 150.0, the preference | 214.3, converts to ordinary shares |
At the lower exit the preference takes more than the investor’s percentage, and the ordinary shareholders receive less. At a ₹600 crore equity exit, 1/7 converts into only ₹85.7 crore, so this investor instead takes the ₹150 crore preference. The remaining ₹450 crore is then allocated under the other share terms. At ₹1,500 crore, conversion gives ₹214.3 crore, which exceeds the preference. Investors notice, and founders who disclose the waterfall early are in a stronger position when the term sheet is negotiated.
Anti-dilution protection changes the next round
Many preference terms include anti-dilution protection that adjusts the conversion price if a later round is priced lower. A down round can therefore transfer value to earlier investors even when the company grows. The deck for the next round must show the effect of the anti-dilution term on the new investor’s stake, not only the headline price.
Which Indian Issue-Pricing Rules Apply to the Round?
A negotiated fundraising value, a company-law report and a tax valuation do not serve the same purpose. Map the transaction, investor residency, instrument and date before deciding which reports and approvals apply. A commercial DCF is not automatically the prescribed tax value.
Company-law approvals and the price basis
Company-Law and Recipient-Side Checks
| Requirement | What to check | What belongs in the round pack |
|---|---|---|
| Companies Act, 2013: Sections 42 and 62(1)(c) | For a preferential issue, review Rule 13 of the Share Capital and Debentures Rules and the private-placement requirements under Rule 14 of the Prospectus and Allotment Rules. | Applicable shareholder approval, a registered-valuer report for the preferential issue, offer/allotment records and required filings. Confirm the route with company counsel. |
| Income-tax Act, 2025: Section 92(2)(m) | Receipt of property below prescribed value can have recipient-side tax consequences, subject to thresholds, exclusions and the transaction facts. | Assess applicability rather than claiming that every resident subscription requires the same tax report. |
Current tax valuation and the former angel-tax provision
Where a relevant tax provision requires fair market value, Rule 57 of the Income-tax Rules, 2026 applies by property category. For unquoted equity, the specified method is an adjusted net-asset formula, not a free choice between DCF and net asset value. Other unquoted securities have a separate treatment. Check the instrument and applicable valuation date. The new Act and Rules apply from 1 April 2026, with transition rules for earlier periods.
The former company-side angel-tax provision, Section 56(2)(viib) of the 1961 Act, was switched off from assessment year 2025–26 by the Finance (No. 2) Act, 2024. That does not remove company-law, recipient-side tax or FEMA requirements. Legacy Rule 11UA should not be presented as a universal current fundraising requirement.
Foreign-investor pricing and reporting
For an unlisted-company issue to a non-resident covered by the pricing rules, FEMA generally sets a floor based on an arm’s-length, internationally accepted valuation method. Certification may be by a Chartered Accountant, SEBI-registered merchant banker or practising Cost Accountant. A resident-to-non-resident share transfer generally has a floor; the reverse generally has a ceiling. Check exemptions, sector rules and the actual route. Confirm certificate validity and FC-GPR reporting with the authorised dealer bank before closing.
Check the Reports Your Fundraising Round Actually Needs
Share the investor residency, instrument, cap table and proposed issue terms. Elite Valuation can scope the company-law valuation, applicable tax work and FEMA pricing support, identifying any specialist sign-off needed for the transaction.
Request an Issue-Pricing Scope ReviewFundraising Valuation | Company-Law Reports | Tax Valuation | FEMA Pricing
How Does the Pitch Change for a Pre-IPO Round or an IPO?
A pre-IPO investor buys into a company preparing for a possible listing. The timetable and any discount are negotiated assumptions, not a promise that the IPO will happen or achieve a particular price. The pitch must therefore show the route to listing, the eligibility, the numbers that will appear in the offer document, and the basis for the pre-IPO placement price. A pre-IPO price that sits far above the eventual issue price, or far below it without explanation, invites questions from the investor, the underwriters and the regulator.
The SEBI Issue of Capital and Disclosure Requirements (ICDR) Regulations, 2018 set the eligibility tests that a company must meet before a public issue, and they regulate pre-IPO placements. The restrictions on pre-IPO placements, including any cap and the time limits, must be read from the current regulation before a placement is priced. The deck should therefore state the listing timetable, the eligibility route that the company expects to use, and the reconciliation between the pre-IPO price and the price band that will be proposed.
What an IPO-bound deck must add to a private round deck
- Restated or audited financials. The numbers in the deck must match the figures that will appear in the offer document, with the restatements explained.
- Pre-IPO price reconciliation. The pre-IPO price is set against the proposed price band, using a method that the underwriters and the auditors can follow.
- Peer set for the listing. Listed peers, with the multiples used and the reasons the company should trade within or outside the range.
- Governance and disclosures. Board composition, related-party arrangements, ESOP grants and the lock-in position of each shareholder.
How Should an Exit Be Pitched to Buyers and Investors?
An exit pitch is written for a buyer that will own the cash flows, not for a minority investor that is buying a share of growth. A strategic buyer assesses potential synergies; how much of that value reaches the seller depends on negotiation and execution risk. A financial buyer, such as a private equity fund, prices the business on its cash flows and its ability to return the fund’s capital with the expected return, after debt. The deck for each type of buyer should lead with different numbers.
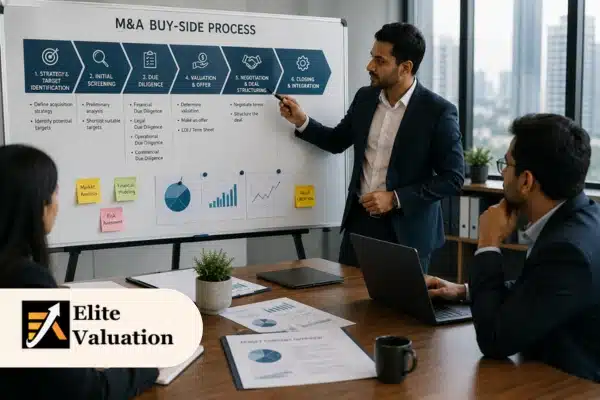
Where a foreign buyer acquires shares from a resident shareholder, the price must meet the pricing rules under the FEMA NDI Rules, 2019, and the seller and buyer must file the transfer as the rules require. Where a non-resident seller exits to a resident buyer, the ceiling applies. The Valuation that supports the exit price should therefore be prepared on the same basis as the buyer’s due diligence, so that the price does not change during the process. Our M&A buy-side process guide covers the diligence steps on the buyer side, and the purchase price allocation guide covers the accounting that follows the deal.
The buyer’s diligence finds what the deck left out
Buyers test the same numbers as investors, and they add the customer contracts, the employee terms, the intellectual property and the tax position. A deck that has not been reconciled to the data room will lose time and price during exclusivity. Prepare the data room and the reconciliation before the first buyer meeting, not after the buyer asks for them.
Pitch Deck Valuation Services From Elite Valuation for Series A, B, C, IPO and Exit
Elite Valuation is an independent Valuation firm founded in 2020 by Sagar Shah, a Chartered Accountant, Company Secretary and IBBI Registered Valuer, who holds an All India Rank in the CA examination. Before founding the firm he spent 9 years at Ernst & Young focused on cross-border structuring and transfer pricing, which are the questions that arise when a growth-stage company takes foreign money, issues shares to non-residents or prepares for a sale to a foreign buyer. The firm’s practice covers business Valuation, M&A advisory, purchase price allocation, ESOP Valuation and advisory, FEMA, SEBI and Income Tax Valuations, financial modelling, DCF analysis and purpose-specific tax valuation reports.
A growth-stage round is a Valuation, a cap table, a tax position and a set of foreign exchange rules at the same time. Elite Valuation prepares these on one consistent set of assumptions, so that the Valuation slide, the dilution table, the applicable statutory valuation reports and the FEMA pricing support all describe the same company. The table below sets out the services and where each one sits in this guide.
Advisory Deliverables
| Need | What Elite Valuation delivers | Where it sits in this guide |
|---|---|---|
| Valuation slide review for a round | Reconciliation of pre-money, round size, post-money and the investor’s stake, with the method and range tested | Valuation slide section |
| Metrics and definitions appendix | Definition sheet, ARR bridge and reconciliation of management accounts to audited or reviewed figures | Numbers section |
| Dilution and ESOP top-up model | Cap table across the planned rounds, with the ESOP pool and the effective pre-money for existing holders | Dilution section |
| Preference and waterfall analysis | Payout at a range of exit values for each class of shares, including anti-dilution effects | Preference section |
| Purpose-specific tax and FEMA pricing support | Applicable company-law valuation, tax valuation under the current rules where required, and FEMA pricing support for covered non-resident issues | Indian rules section |
| Pre-IPO and IPO price reconciliation | Pre-IPO price set against the proposed price band, with listed peers and the restated figures | IPO section |
| Exit Valuation and purchase price allocation | Value of the business for a sale, and the purchase price allocation the buyer will need after completion | Exit section |
Why clients choose Elite Valuation for growth-stage rounds, IPOs and exits
- Credentials in three disciplines. The founder is a Chartered Accountant, a Company Secretary and an IBBI Registered Valuer, and holds an All India Rank in the CA examination.
- Cross-border depth. 9 years at Ernst & Young on cross-border structuring shapes how the firm handles foreign investors, offshore holding structures and the FEMA position of each issue or transfer.
- Practice in the rules that drive the number. Applicable income-tax valuation rules, the FEMA NDI Rules, Ind AS 102, 103, 109, 113 and 36, and IBC Valuations form part of the firm’s regular work.
- Documented scope and working papers. Each engagement runs to a written scope, with documented assumptions, a sensitivity range and retained working papers.
- One set of numbers across the round. The deck, the cap table, the applicable statutory valuation reports and the FEMA support are kept consistent, so that diligence finds one story.
Start a Growth-Stage Valuation Scope With Elite Valuation
Share the latest management accounts, the cap table, the proposed term sheet and the investor list. Elite Valuation confirms the purpose, the method, the reports needed for the round, the FEMA position for any foreign investor, and sends a written fee after that call.
Book a Growth-Stage Scope CallPitch Deck Valuation | Series A, B and C Rounds | Statutory Valuation | FEMA Pricing | Pre-IPO Valuation | Exit Valuation
How to Choose a Valuation Adviser for a Growth-Stage Round in India: A Verifiable Checklist
The adviser for a growth-stage round will be reviewed by the lead investor, its counsel, the auditor and, for a foreign investor, the bank that processes the filing. The checks below are the ones those parties will make, so they are the checks to make first. The table sets out each check and the warning sign that should pause the engagement.
Choosing the Right Valuation Adviser
| Check | What to ask for | Warning sign |
|---|---|---|
| Credentials for the report purpose | Relevant registration and asset class for the company-law report, and the separate qualifications accepted for any tax or FEMA certification | Credentials that do not meet the particular report’s statutory purpose |
| Transaction-purpose and FEMA experience | Examples of fair market value and pricing reports prepared for unlisted issues, described by purpose | A single headline value with no method, inputs or sensitivity |
| Preference and CCPS experience | Experience valuing preference shares, anti-dilution and the waterfall, with the Ind AS 109 classification | A Valuation that treats all shares as ordinary equity without discussing the preference terms |
| Scope and deliverable | A written scope, the assumptions to be tested, the sensitivity range, the signed report and the review process | A one-page opinion with no stated assumptions, or a value described as guaranteed |
| Independence | A written conflict declaration covering the lead investor, the other investors and the company’s advisers | A fee linked to the value reported, or no conflict check |
Choosing the Right Valuation Adviser: Coordination with counsel and the auditor
| Check | What to ask for | Warning sign |
|---|---|---|
| Coordination with counsel and the auditor | A plan for how the figures reach the term sheet, the auditor and the filing | No plan, or a request to change the books or the forecast to fit the price |
A sequence for shortlisting an adviser for the round
- Write down the stage, the round size, the expected pre-money, the investor type and whether any investor is a non-resident.
- Shortlist three firms and check each signing person’s IBBI registration and asset class.
- Ask each firm for the scope, the method, the data it needs and the time before the term sheet deadline.
- Ask for the structure of a sample report with client details removed, including the waterfall and the reconciliation.
- Compare the scope, the timeline, the signing person and the conflict declaration, not the headline fee alone.
- Sign an engagement letter that names the purpose, the standard of value, the cut-off date and the intended users.
How to Prepare the Valuation and Numbers Pack for a Round in Seven Steps
A round that closes quickly is usually one where the numbers were ready before the first investor meeting. The seven steps below set the order in which the pack should be prepared, so that the deck, the diligence and the filing use one version of the figures.
Seven steps from first meeting to filing
- Fix the stage and the purpose. Decide whether the report supports a round, an IPO, a sale or an issue to a resident or non-resident, and name the users.
- Reconcile the management accounts. Tie the figures in the deck to the audited or reviewed accounts, and explain each difference in a short note.
- Rebuild the ARR and the metrics. Build the ARR bridge, the cohort retention and the unit economics from contracts and receipts, with the definitions written down.
- Model the cap table and the waterfall. Show dilution across the planned rounds, the ESOP top-up, the preference terms and the payout at three exit values.
- Prepare the Valuation and the range. Build the methods, test the inputs, and state the range the deck will show, with the sensitivity behind it.
- Clear the issue rules. Prepare the applicable statutory valuation reports for unlisted shares, the FEMA pricing support for each non-resident investor, and the company law steps for the private placement.
- Lock the data room and the filing. Put the Valuation, the reconciliation and the approvals in the data room, and file the returns and reports within the prescribed time.
Where Growth-Stage Companies Go Wrong With Pitch Decks: Common Mistakes and Fixes
Most growth-stage rounds stall on the same few points. The seven below appear most often when a term sheet is renegotiated, a data room is opened or an underwriter asks for the bridge between the pitch and the filing. They are listed in order of how much damage each one does to the price or the timetable.
Presenting the last round as the Valuation
The deck opens with the price of the previous round and expects it to carry the new one, without explaining what has changed in revenue, margin, retention or the preference terms.
New price challenged in the first meetingSet out what has changed since the last round in four or five measurable items, and build the new range from methods that do not depend on the prior price.
Quoting the pre-money without the ESOP top-up
The deck quotes the pre-money but omits a pool that the investor expects inside that amount. Existing holders then bear the unshown pool dilution before the investor subscribes.
Price reopened in the term sheetState the pool size, whether it sits in the pre-money, and the effective pre-money for existing holders, on the same slide as the headline Valuation.
Showing the stake without the preference waterfall
The deck states the investor’s percentage of the company, but the liquidation preference takes more than that percentage at a lower exit, so the payout to ordinary shareholders may be overstated.
Investor trust lost in diligenceShow the payout to each class of shares at three exit values, including one below the post-money, and state whether each preference is participating or senior.
Agreeing a foreign investor’s price before the FEMA floor is tested
The term sheet fixes a price for a non-resident investor, and the pricing support under the FEMA NDI Rules is prepared only after signing, so the price may sit below the permitted floor.
Pricing breach and reporting delayObtain the pricing support for each non-resident issue before the term sheet is signed, and make the price subject to that support in the agreement.
Assuming one valuation report covers every statutory purpose
The team treats its negotiated fundraising value as sufficient for company law, recipient-side tax and FEMA without testing which rules apply to the instrument and the parties.
Tax exposure on the recipientMap each applicable provision, date, valuation method and certifying professional before relying on a report for the issue.
Using different ARR definitions in the deck and the data room
The pitch counts one-time fees as recurring, while the data room shows the contracted base, so diligence finds a gap and the buyer or investor restates the revenue.
Price cut at diligencePublish one definition sheet and one ARR bridge, and use them in the deck, the appendix and the data room without change.
Setting a pre-IPO price with no link to the issue price
The pre-IPO placement is priced at a level that cannot be reconciled with the proposed price band, the listed peers or the restated financials in the offer document.
Questions from underwriters and the regulatorReconcile the pre-IPO price to the proposed price band through the peer set and the restated financials before the placement is offered.
What should a growth-stage company take from its pitch deck Valuation?
A Series A, B or C pitch deck, and the IPO or sale that follows, is a set of linked numbers. The Valuation slide, the dilution table, the preference waterfall, the metrics appendix and the Indian filings must describe the same company. When they do, the round is priced on the business rather than on the questions the investor asked first.
The points that most often decide the result are the basis of the price, the effective pre-money after the ESOP top-up, the payout under the preference terms, the applicable recipient-side tax position, the FEMA pricing for non-residents, and the reconciliation of the pre-IPO price to the issue price. Each one can be checked before the term sheet is signed, and each one is cheaper to fix then than in diligence.
Elite Valuation prepares the Valuation, the dilution and waterfall analysis, the applicable tax and FEMA support, and the pre-IPO and exit Valuations on one set of assumptions, so that the company presents one number, defends it with one reconciliation, and carries it through the data room and the filing.
Preparing a Series A, B or C Round, an IPO or a Sale?
Elite Valuation starts with the management accounts, the cap table and the proposed term sheet, then confirms the Valuation, the waterfall and the issue rules that the round needs. Share those documents to start a scope discussion.
Speak to Elite ValuationPitch Deck Valuation | Series A, B and C Rounds | Statutory Valuation | FEMA Pricing | Pre-IPO Valuation | Exit Valuation
Frequently asked questions about pitch decks and Valuation for growth-stage rounds
What should a Series B pitch deck include in India?
A Series B pitch deck in India should include the Valuation slide with pre-money, round size, post-money and the investor’s stake, a Valuation range built from more than one method, the metrics that investors test, including ARR, net revenue retention, gross margin, burn multiple, CAC payback and cash runway, and the use of funds tied to milestones. It should also carry an appendix with metric definitions, an ARR bridge and a reconciliation of management accounts to audited or reviewed figures, so that the numbers can be checked before the first term sheet.
How is pre-money Valuation different from post-money Valuation?
Pre-money Valuation is the value of the company before the new money comes in. Post-money Valuation is the pre-money plus the amount raised. The new investor’s stake equals the amount raised divided by the post-money Valuation. For example, a ₹80 crore round at a ₹400 crore pre-money gives a post-money of ₹480 crore and an investor stake of 16.7 per cent, before any ESOP top-up. The deck should show both figures, because the post-money is the basis for the stake.
How much dilution does a Series A round cost the founders?
Dilution in a Series A round equals the new investor’s stake, which depends on the round size and the post-money Valuation, plus any ESOP top-up that is issued at the same time. The existing holders’ stake falls by the same proportion. The percentage for each round depends on the company’s own figures, so the deck should show a cap table across the planned Series A, B and C rounds, not a single round, and state the assumptions behind the dilution.
Should the ESOP top-up sit in the pre-money Valuation?
Investors often ask for the ESOP pool to be topped up before the round, so that the new pool is included in the pre-money. The effect is that existing shareholders bear the dilution of the new pool, and the effective pre-money for existing holders is lower than the stated figure. The Valuation slide should state the pool size, whether it sits in the pre-money, and the effective pre-money, so that the price is not reopened in the term sheet.
What is a liquidation preference and why does it matter in a pitch?
A liquidation preference gives a preferred shareholder, usually a holder of compulsorily convertible preference shares, a right to receive a set amount before ordinary shareholders at an exit. A 1x non-participating preference returns the amount invested or converts to ordinary shares, whichever gives the greater payout. At a lower exit the preference can take more than the investor’s percentage of the company, so the pitch must show the payout at several exit values, not only the stake.
Does every Series C round need the same tax valuation report?
No. Identify the transaction, instrument, date and applicable provisions first. For current transactions, use the Income-tax Act, 2025 and the Income-tax Rules, 2026 where applicable. Rule 57 prescribes property-specific methods and does not give unquoted equity a general DCF option. Company-law and FEMA reports have distinct purposes. The former angel-tax rule is not a universal current issue-price test.
Which FEMA pricing rules apply when a foreign investor buys shares?
The applicable FEMA NDI pricing rules govern shares issued to, or transferred by, non-residents, with a floor and a ceiling set by Valuation under the pricing guidelines. The pricing support should be obtained from a qualified professional, and the method and the Valuation date should be recorded for each foreign issue. The issue must then be reported to the Reserve Bank of India within the time prescribed. The current list of certifying professionals and the reporting timeline should be confirmed before each filing.
What changes in the pitch before an IPO?
Before an IPO the pitch must match the offer document, so the figures should be restated or audited, the metrics should be defined as they will appear in the prospectus, and the pre-IPO placement price must be reconciled to the proposed price band through listed peers and the restated financials. The company must also meet the eligibility tests under the SEBI Issue of Capital and Disclosure Requirements Regulations, 2018, and any pre-IPO placement must follow the restrictions in those regulations.
How should a company present an exit to buyers?
An exit pitch should be written for the buyer that will own the cash flows. A strategic buyer looks for synergies, and a financial buyer prices the business on its cash flows after debt. The deck should show normalised earnings, clean customer contracts and a data room that matches the figures. Where a non-resident buyer acquires shares from a resident seller, or the reverse, the price must meet the FEMA pricing rules, and the Valuation should be prepared on the same basis as the buyer’s diligence.
Who should prepare the Valuation for a growth-stage round in India?
Choose the professional by the report’s purpose. A preferential-issue company-law report requires an appropriately registered valuer. Covered unlisted-share FEMA pricing can be certified by a Chartered Accountant, SEBI-registered merchant banker or practising Cost Accountant. Tax and accounting work have their own requirements. Confirm independence, relevant registration, instrument expertise and a written scope rather than assuming one credential covers every report.
Sources
Read the current provisions and transaction-specific exceptions with your company counsel, tax adviser and authorised dealer bank.
- Companies Act and rules — Ministry of Corporate Affairs: preferential issues, private placement, approvals and registered-valuer requirements.
- Income-tax Act, 2025 — Section 92: recipient-side property provisions, thresholds and exclusions.
- Notified Income-tax Rules, 2026: Rules 56 and 57, valuation dates and property-specific methods.
- RBI Master Direction — Foreign Investment in India: issue and transfer pricing, certifying professionals and applicable exceptions.
- SEBI regulations — current ICDR framework: eligibility and disclosures for public issues; select the current ICDR text.
Plan the Valuation and Numbers Behind Your Next Round, IPO or Sale
Whether the company is raising a Series A, B or C round, preparing for a listing or planning a sale, Elite Valuation prepares the Valuation, the dilution and waterfall analysis and the Indian issue rules on one set of assumptions, so the pitch, the data room and the filing carry the same numbers.
Book a Growth-Stage Valuation CallPitch Deck Valuation | Series A, B and C Rounds | Statutory Valuation | FEMA Pricing | Pre-IPO Valuation | Exit Valuation
Disclaimer. This article is general information only. It is not legal, tax, accounting or investment advice, and it is not a Valuation of any company, share or round. The figures in the tables and the figure are hypothetical and do not describe any transaction. The Companies Act, Income-tax Act, FEMA NDI Rules and SEBI ICDR Regulations change, and the points flagged in the sources must be checked against the current text before reliance. Editorial review: 30 October 2026. Verify transaction-date applicability before reliance. Confirm each point with a qualified professional before relying on it.